

What if your 50th birthday wasn’t just a milestone, but the start of your most powerful financial decade yet? For many Australians, reaching this age brings a mix of excitement and a sudden, sharp focus on the future. You might find yourself wondering if you’ve done enough or if the “retirement gap” is a hurdle you can actually clear. When looking at financial planning for 50 year olds in Australia, it’s completely natural to feel a bit of anxiety about shifting superannuation caps or the weight of a mortgage as you head toward your sixties.
We believe these years should be about confidence rather than confusion. You’ve worked hard to provide for others, and now it’s time to ensure your wealth is working just as hard for you. This guide will show you how to optimise your super under the 2026 contribution limits, reduce debt, and legally minimise your tax to protect your future lifestyle. We’ll walk through a strategic checklist for your next ten years, giving you a clear roadmap to transition from work to a retirement that feels both secure and rewarding.
Key Takeaways
- Discover why your 50s are considered the “Power Decade” and how to use this pivotal time to secure your long-term lifestyle.
- Learn how tailored financial planning for 50 year olds in Australia shifts the focus from simply saving to organising your assets for maximum efficiency.
- Understand the strategic balance between growth and consolidation, ensuring your portfolio remains resilient against inflation without taking unnecessary risks.
- Uncover how to navigate the 2026 superannuation contribution caps and utilise carry-forward rules to boost your retirement savings legally.
- Explore the benefits of integrating tax preparation with your wealth strategy to create a seamless, future-proof financial roadmap.
Why the Age 50 Milestone is Your Strategic Pivot Point
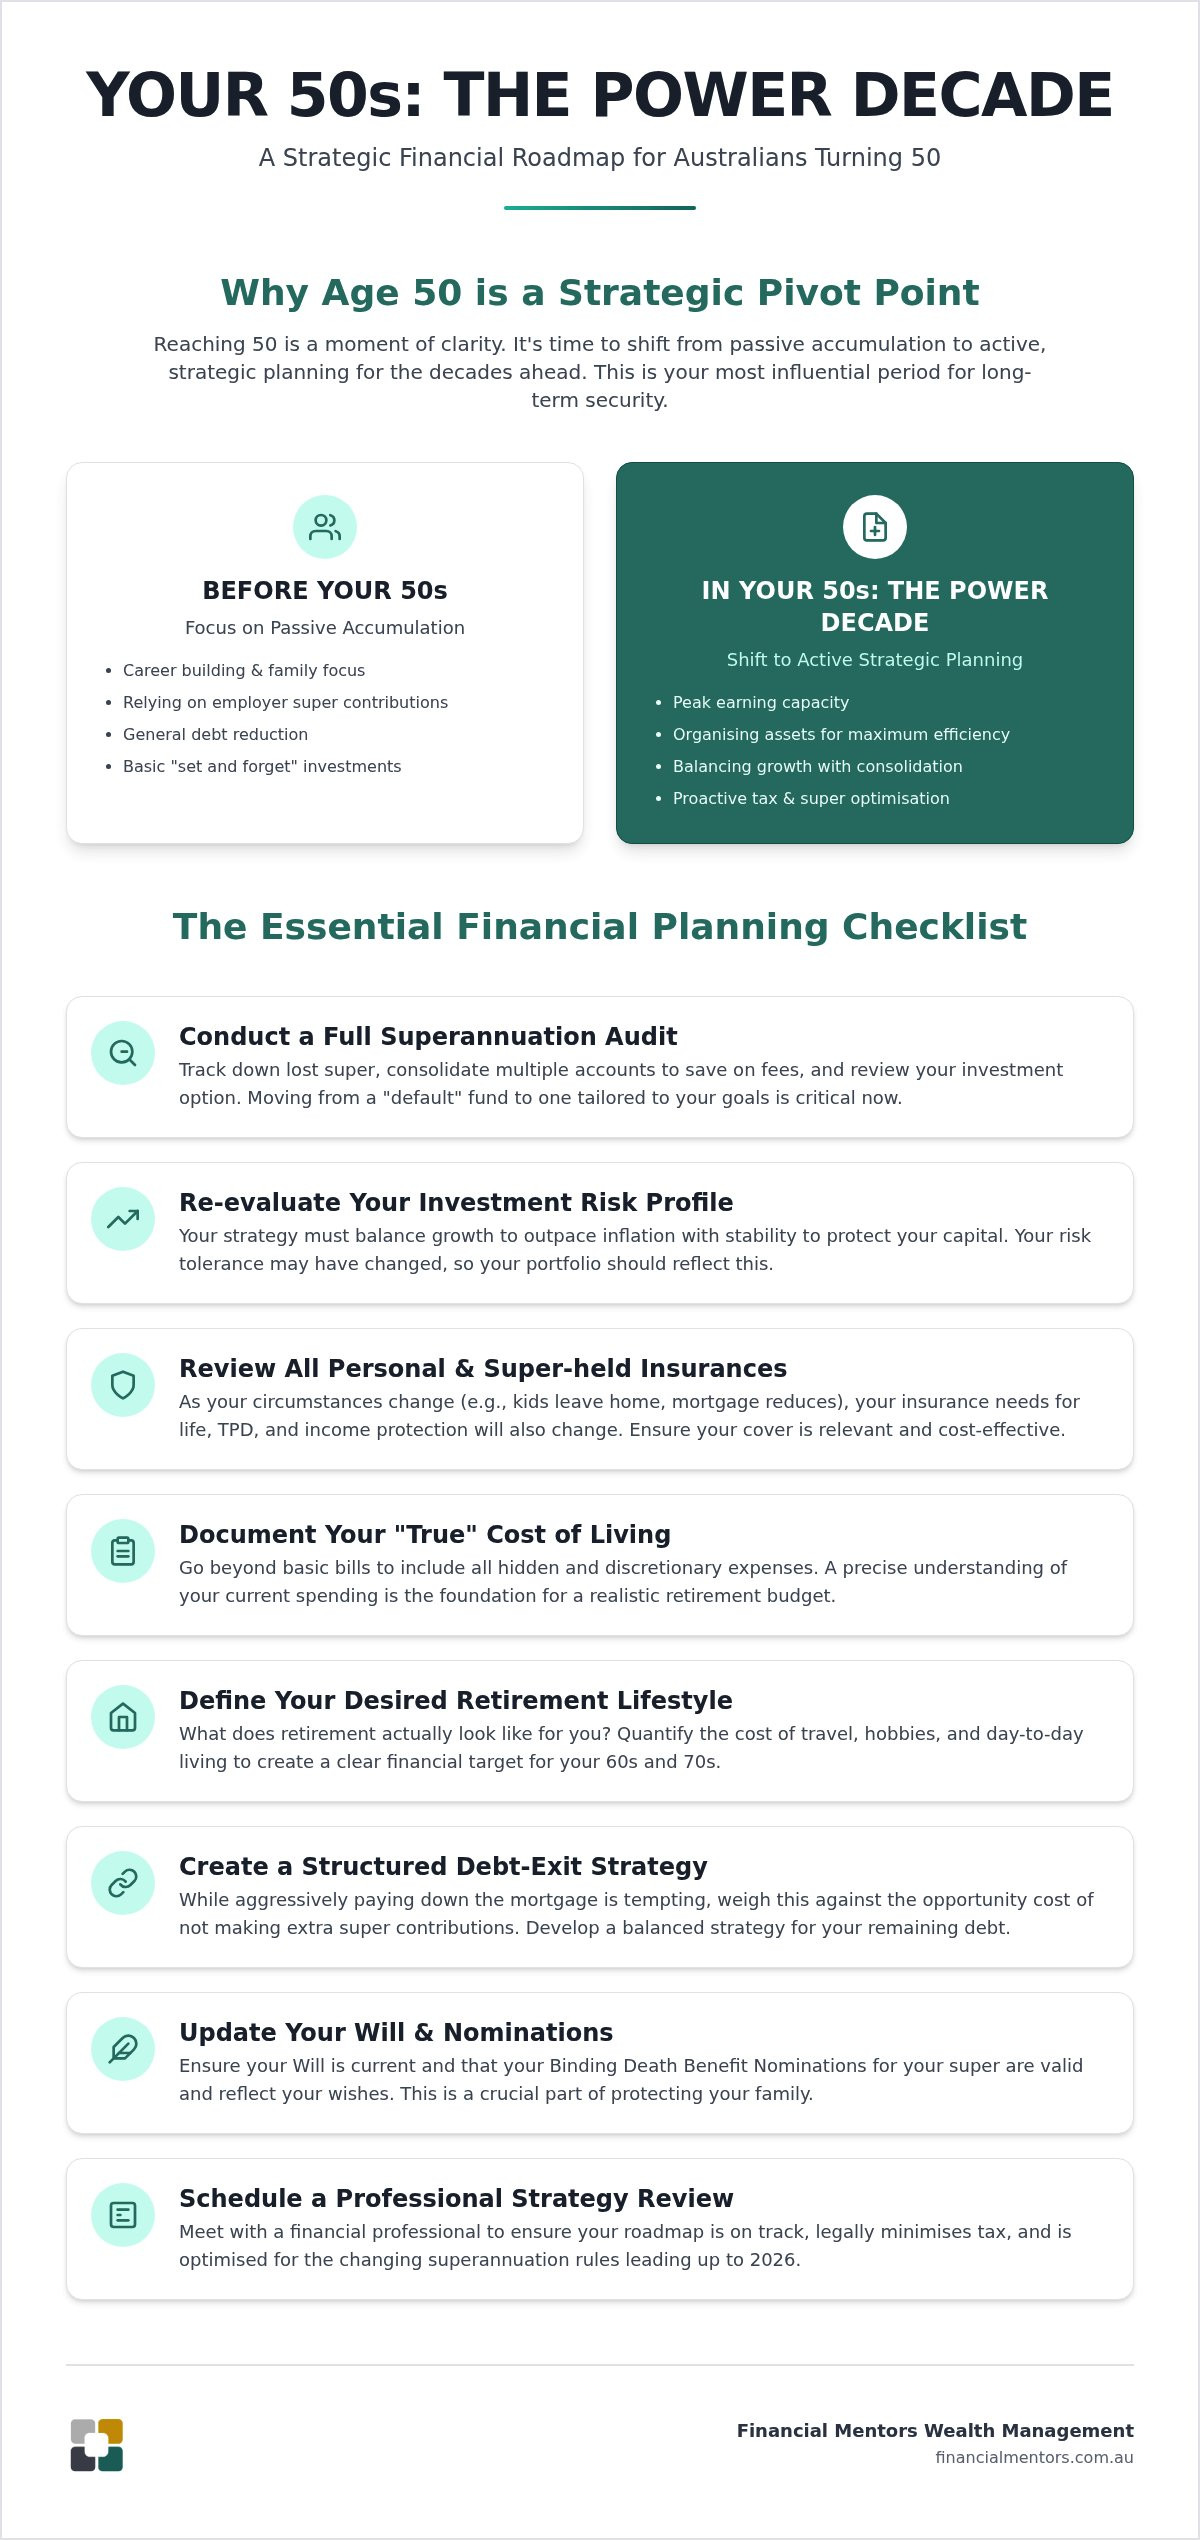
Reaching 50 is often described as a moment of sudden clarity. You’ve likely spent decades building a career, raising a family, and managing the day-to-day. Suddenly, the horizon looks different. This “50-year-old epiphany” isn’t about fear; it’s about realisation. You’re entering what we call the “Power Decade.” This ten-year window is perhaps the most influential period for your long-term security, as it’s when your earning capacity is often at its peak and your expenses may finally be stabilising.
Effective financial planning for 50 year olds in Australia involves a deliberate shift from passive accumulation to active strategic planning. You can no longer just let your employer’s contributions do the heavy lifting while you hope for the best. The 2026 financial landscape, with its updated contribution caps and tax rules, rewards those who take a proactive approach. If you act now, you can leverage these rules to significantly boost your position before you reach your 60s.
The Reality of the Retirement Gap in Australia
Many Australians face a significant gap between their current super balance and the lifestyle they envision for their future. With life expectancy in Australia now reaching 81.1 years for men and 85.1 years for women according to the Australian Bureau of Statistics, your savings might need to last three decades or more. Relying on the old “she’ll be right” attitude is a risky path. If you don’t account for the way inflation erodes your purchasing power by 2040, a nest egg that looks large today might only cover the basics tomorrow. Understanding the rules of Superannuation in Australia is the first step in ensuring your “gap” doesn’t become a crisis.
Shifting from Debt Reduction to Wealth Creation
Carrying a mortgage into your 50s can feel like a heavy psychological burden. While your instinct might be to funnel every spare cent into the home loan, there’s a significant opportunity cost to consider. If you focus solely on debt, you might miss out on the tax-effective growth available within your super. Adopting a wealth creation strategies australia approach helps you evaluate whether paying off the house or boosting your retirement savings will change your long-term trajectory more effectively. It’s about finding the balance that offers both peace of mind and financial freedom. This is where professional financial planning for 50 year olds in Australia becomes truly transformative, helping you decide exactly where your next dollar does the most work for your future self.
The Essential Financial Planning Checklist for Australians in Their 50s
Effective financial planning for 50 year olds in Australia is rarely about finding a “get rich quick” scheme. It’s about the steady, methodical organisation of what you’ve already built. Think of this stage as a professional audit of your life’s work. To help you move forward with confidence, we’ve identified eight essential actions for your strategy checklist:
- Conduct a full superannuation audit and consolidate multiple accounts.
- Re-evaluate your investment risk profile to balance growth and stability.
- Review all personal and super-held insurances for current relevance.
- Document your current “true” cost of living including all hidden expenses.
- Define a clear, desired retirement lifestyle budget for your 60s and 70s.
- Create a structured debt-exit strategy for your remaining mortgage.
- Update your Will and Binding Death Benefit Nominations.
- Schedule a professional strategy review to ensure your roadmap is on track.
Organising these details now creates a foundation for the next fifteen years. It’s helpful to see these points as part of a wider retirement planning checklist australia designed to carry you through the long haul.
The Superannuation Audit: Beyond the Balance
Is your superannuation truly working for you? Many people reach their 50s only to realise they are still in a “default” investment option. While this may have served you well in your 30s, your 50s require a more tailored approach. Checking for lost super and consolidating accounts can save thousands in duplicated fees over the next decade. The ATO guide to super and retirement is an excellent resource to help you track down forgotten funds. Don’t forget to assess your insurance; as your children become independent, the level of life cover you needed ten years ago might no longer be necessary.
The Lifestyle and Spending Review
When considering financial planning for 50 year olds in Australia, it’s easy for “lifestyle creep” to set in as your income peaks. Small, recurring expenses can quietly erode the funds you could be using for wealth creation. Take a moment to calculate what you actually spend each month versus what you hope to spend when you stop working. Setting a clear, measurable financial target for your 60th birthday gives you a tangible goal to work toward. This clarity reduces the anxiety of the unknown and replaces it with a sense of control.
Estate Planning: Protecting the Legacy
A simple Will often fails to address the complexities of modern Australian families. This is particularly true for your superannuation; your Will doesn’t automatically cover your super balance. You need a valid Binding Death Benefit Nomination (BDBN) to ensure your legacy goes exactly where you intend. Seeking professional estate planning advice early ensures your family is protected and your wishes are legally sound. If you’re ready to start organising your future, speaking with a specialised wealth management office can make the entire process much simpler.
Comparing Growth vs. Consolidation: Where Should Your Focus Lie?
One of the biggest myths we encounter is that once you hit 50, it’s time to move everything into the safety of cash. While protecting what you’ve built is important, your 50s are not the finish line. In fact, for many, this is only the halfway point of their investment journey. According to the Australian Bureau of Statistics, a 60-year-old man can expect to live another 24.2 years on average, and a woman another 27.1 years. If you move to a conservative “all-cash” position too early, you risk your purchasing power being eroded by inflation over those three decades.
We often recommend a “bucket strategy” when helping with financial planning for 50 year olds in Australia. This approach organises your wealth into different pools based on when you’ll need the money. You might keep enough cash for your first few years of retirement in a “liquid” bucket, while leaving the remainder in growth-oriented assets to ensure your nest egg continues to compound. This balance allows you to sleep soundly during market volatility while still giving your super the fuel it needs to last. Different risk profiles will lead to very different planned retirement outcomes, so it’s vital to model these scenarios before making a permanent shift.
If you’re unsure how your current assets align with government support, checking the Services Australia retirement planning resources can provide clarity on how your private savings interact with the Age Pension, which remains age 67 for those born after 1957.
Transition to Retirement (TTR) Strategies
A TTR strategy is a powerful tool for those in their late 50s. It allows you to access a portion of your super as a pension while you’re still working, provided you’ve reached your preservation age. In 2026, many Australians use this to “recycle” their income. You can salary sacrifice more of your pay into the low-tax super environment (up to the $32,500 concessional cap) and replace that take-home pay with a tax-effective TTR pension. This can boost your super balance significantly in those final working years without affecting your daily lifestyle.
The Downsizer Contribution: A 50s Planning Tool?
While you might not be ready to move just yet, the downsizer contribution is a critical element of financial planning for 50 year olds in Australia. Eligible individuals aged 55 and over can now contribute up to $300,000 from the sale of their primary residence into their super. This is an “extra” contribution that doesn’t count toward your standard caps. If you’re planning to move to a smaller home or a different location in your late 50s or early 60s, this strategy can provide a massive, tax-effective boost to your retirement fund late in the game.
Navigating Superannuation Caps and Tax Optimisation Before 60
If you’ve spent your 40s focusing on growth, your 50s are the time to get surgical about tax. Understanding the rules of financial planning for 50 year olds in Australia means looking beyond just the numbers in your bank account and focusing on the net outcome after the taxman takes his share. For the 2026-2027 financial year, the concessional contribution cap has increased to $32,500. This remains your most powerful tool for reducing your taxable income while simultaneously building your future.
Many people don’t realise they can “catch up” on missed opportunities. If your total super balance was under $500,000 on 30 June 2026, you might be eligible for the carry-forward rule. This allows you to use any part of your concessional cap that went unused over the previous five years. It’s a fantastic way to make a larger contribution if you’ve recently received a bonus or sold an asset. This level of detail is why your tax return preparation shouldn’t be a standalone task. It needs to be an integrated part of your broader wealth plan.
High-income earners also need to be mindful of Division 293 tax and the new Division 296 tax effective from 1 July 2026. These rules apply additional taxes to contributions and earnings for those with higher income or balances exceeding $3 million. While these can feel like a penalty for success, a mentor can help you structure your affairs to manage these costs effectively. By looking at your household as a single financial unit, you can often find ways to keep more of your hard-earned money.
Maximising Concessional Contributions
Salary sacrifice is often the simplest way to lower your tax bill. By directing a portion of your pre-tax salary into super, you’re only taxed at 15% on that money, rather than your marginal rate. If you’re a business owner or have irregular income, personal deductible contributions offer similar benefits. You simply make a contribution and claim it as a tax deduction. Over the next decade, the compounding effect of these tax savings can add significant value to your final retirement nest egg.
Spouse Splitting and Co-contributions
Effective financial planning for 50 year olds in Australia is often a team effort. Spouse splitting allows you to transfer up to 85% of your concessional contributions to your partner’s account. This is a brilliant way to equalise balances, especially if one person is nearing the $2.1 million Transfer Balance Cap. If your spouse is a lower earner, don’t overlook the government co-contribution. A small non-concessional contribution could trigger a “free” boost from the government, helping both of you move toward your goals together.
Ready to see how these 2026 caps apply to your specific situation? Our team can help you optimise your tax strategy and ensure your super is working as hard as possible before you reach 60.
How a Mentor Helps You Organise Your Wealth for the Long Haul
As you move through your 50s, the sheer volume of financial information can feel overwhelming. It’s one thing to read about contribution caps or tax rules; it’s another to weave them into a life that feels balanced and secure. This is where the value of a partner becomes clear. Effective financial planning for 50 year olds in Australia isn’t just a series of transactions. It’s a relationship based on stewardship and a shared vision for your future.
A transactional broker might help you buy a product, but a mentor helps you build a roadmap. This distinction is vital as you approach the Age Pension age of 67. You need a partner who looks at your whole picture, from your super balance to your family’s estate planning needs. Choosing a wealth management office that understands the nuances of the 2026 landscape provides a level of future-proofing that a simple “do-it-yourself” approach often lacks. Having a professional second opinion ensures that you aren’t just guessing about your future, but moving toward it with quiet confidence.
The Financial Mentors Approach
At Financial Mentors Wealth Management, we act as a trusted guide through your most critical financial years. Murray Frean and our team have been AFSL registered since 2003, specialising in the specific challenges of the transition to retirement. We don’t just look at investments; we focus on strategic wealth creation and personal roadmaps. By integrating tax return preparation with your broader strategy, we ensure your plan is efficient, legal, and focused on your long-term well-being. This methodical approach creates a sense of order and clarity, helping you navigate the emotional nuances of major life changes.
Taking the First Step Toward Your Future
Starting the dialogue is often the most significant step you’ll take. When you come in for your first consultation, bring your current super statements, mortgage details, and a rough idea of the lifestyle you want to lead. The return on investment for professional financial planning for 50 year olds in Australia is measured in more than just percentages. It’s found in the peace of mind that comes from knowing your super is working hard and your legacy is protected. We invite you to start the conversation today to secure your planned retirement and give you the clarity you deserve for the decade ahead.
Securing Your Power Decade for a Confident Future
Your 50s represent a unique window of opportunity where every strategic choice you make today can compound into a significantly more comfortable tomorrow. By organising your assets now, you can move away from the anxiety of the retirement gap and toward the peace of mind that comes from being prepared. Whether it’s maximising your 2026 super contributions, refining your estate plan, or de-risking your portfolio, taking action today ensures you aren’t leaving your future to chance. Each step you take to organise your wealth creates a stronger foundation for the years ahead.
Effective financial planning for 50 year olds australia requires a steady hand and a clear, written roadmap. Murray Frean and the team at Financial Mentors Wealth Management bring decades of experience to help you bridge the gap between your current position and your ultimate goals. As specialists in Australian retirement and estate planning, we take a supportive, mentor-led approach to wealth creation that focuses on your unique aspirations. If you’re ready to take control of your next ten years, we invite you to start your journey with a tailored financial roadmap from Financial Mentors Wealth Management. You’ve worked hard to reach this milestone; now it’s time to ensure your future is just as rewarding as the years that led you here.
Frequently Asked Questions
Is 50 too late to start financial planning in Australia?
It’s never too late to begin, and age 50 is actually one of the most effective times to start active planning. You likely have another 15 to 17 years of peak earning potential ahead of you before reaching the Age Pension age. This “Power Decade” allows you to make significant catch-up contributions and refine your strategy while you still have time for compound growth to work in your favour. Starting now ensures your roadmap is ready for the transitions ahead.
How much super should a 50-year-old have in Australia?
The amount you need depends entirely on your desired lifestyle, though many Australians look to the ASFA Retirement Standard as a helpful benchmark for a comfortable retirement. For those currently financial planning for 50 year olds in Australia, having a clear plan to reach your specific target is more important than the balance you have today. If you’re behind, this decade is the ideal time to use strategic contributions and tax-effective growth to bridge the gap.
What are the 2026 superannuation contribution caps?
For the 2026-2027 financial year, the annual concessional contribution cap is $32,500 and the non-concessional cap is $130,000. These limits include your employer’s super guarantee payments and any personal salary sacrifice amounts. If your total super balance was under $500,000 on 30 June 2026, you might also be able to use the carry-forward rule to access unused cap amounts from the previous five years, providing a significant boost to your savings.
Can I access my super at 55 in Australia?
Most Australians turning 50 in 2026 cannot access their super until they reach age 60, which is the current preservation age for those born after June 1964. While you generally can’t withdraw a lump sum or start a pension at 55, there are very specific exceptions for severe financial hardship or permanent incapacity. For the vast majority, age 60 remains the primary milestone for accessing retirement benefits and starting a transition to retirement strategy.
What is the best way to invest $100k at age 50 for retirement?
The most effective way to invest $100,000 often involves a diversified approach that balances growth with long-term tax efficiency. Many people choose to funnel a portion of these funds into superannuation as a non-concessional contribution to take advantage of the low 15% tax rate on investment earnings. The right choice for your financial planning for 50 year olds in Australia depends on your existing debt, your risk tolerance, and how much you’ve already contributed toward your annual caps.
Do I need a financial advisor if I already have a high super balance?
A high balance often brings increased complexity, making professional advice even more valuable to protect your hard-earned wealth. Once your super approaches the $2.1 million Transfer Balance Cap or the $3 million threshold for the Division 296 tax, the rules become much stricter and the tax implications more significant. An advisor acts as a mentor to help you navigate these caps, manage your tax obligations, and ensure your estate planning is robust enough to protect your legacy.
How does the Age Pension asset test affect my planning at 50?
While you might not be eligible for the Age Pension for another 17 years, the asset test is a critical factor in your long-term financial modelling. Your family home is currently exempt from the test, but other investments like super, shares, and investment properties are counted once you reach age 67. Understanding these thresholds now helps you structure your assets to maximise any potential future entitlements. It’s about building a roadmap that considers both your private wealth and government support.
What is a Transition to Retirement (TTR) strategy?
A TTR strategy allows you to access a portion of your super as a pension while you are still working, provided you’ve reached your preservation age. Many Australians use this to “recycle” their income by salary sacrificing more of their pay into the low-tax super environment and replacing that income with a tax-effective TTR pension. This can help you boost your final retirement balance significantly in your 60s without reducing your current take-home pay or affecting your daily lifestyle.