

Did you know that your adult children could lose up to 17 per cent of their inheritance to the tax office, even though Australia technically doesn’t have an inheritance tax? It is a confronting thought for anyone who has spent decades diligently building a nest egg for their family’s future. You likely feel that your hard-earned savings should belong to your loved ones, not the government. If you find the distinction between taxable and tax-free components confusing, you aren’t alone. The complexity of our superannuation system often makes it feel like you’re trying to hit a moving target.
This article will show you how a recontribution strategy for super can help you reduce future tax for your adult children and optimise your retirement income. By acting as a wise steward of your wealth today, you can gain peace of mind knowing your estate is protected. We will walk through the practical steps to rebalance your assets, explain the updated 2026 contribution caps, and provide a clear plan to maximise the tax-free portion of your legacy. It’s about making sure your super works as hard for your children as it did for you.
Key Takeaways
- Understand how a recontribution strategy for super can protect your legacy by converting taxable components into tax-free assets for your beneficiaries.
- Learn why adult children often face a 17 per cent tax bill on inherited super and how you can proactively reduce this burden.
- Identify the specific age and “condition of release” requirements you must meet to legally access and recontribute your funds in 2026.
- Discover how to use current contribution caps to balance super accounts with your spouse, helping to manage your total super balance effectively.
- Recognise the importance of professional guidance to navigate the complex proportioning rules and avoid accidental breaches of ATO limits.
What is a Super Recontribution Strategy and Why Does it Matter?
Have you ever considered that the “type” of money in your super account is just as important as the total balance? While we often focus on the final number, the Australian tax system views your savings through two distinct lenses: taxable and tax-free components. A recontribution strategy for super is the deliberate process of withdrawing a lump sum from your account and immediately gifting it back as a personal, non-concessional contribution. This simple act effectively “washes” your money, changing its status from taxable to tax-free. It is a cornerstone of professional estate planning advice because it addresses a significant tax liability that many families don’t see coming until it is too late. By taking the time to understand these rules, you are essentially building a protective wall around your family’s inheritance.
Think of your super account as a single bucket containing two different colours of money. The “taxable” portion usually comes from your employer’s contributions and any salary sacrifice you’ve made. The “tax-free” portion consists of money you’ve contributed from your own bank account after you’ve already paid income tax on it. Because the ATO has already had its share of the tax-free portion, it can’t tax it again when it leaves the super environment. By using a recontribution strategy for super, you are effectively swapping taxable funds for tax-free funds, ensuring that the “colour” of your money works in your family’s favour.
The “Death Tax” on Superannuation Explained
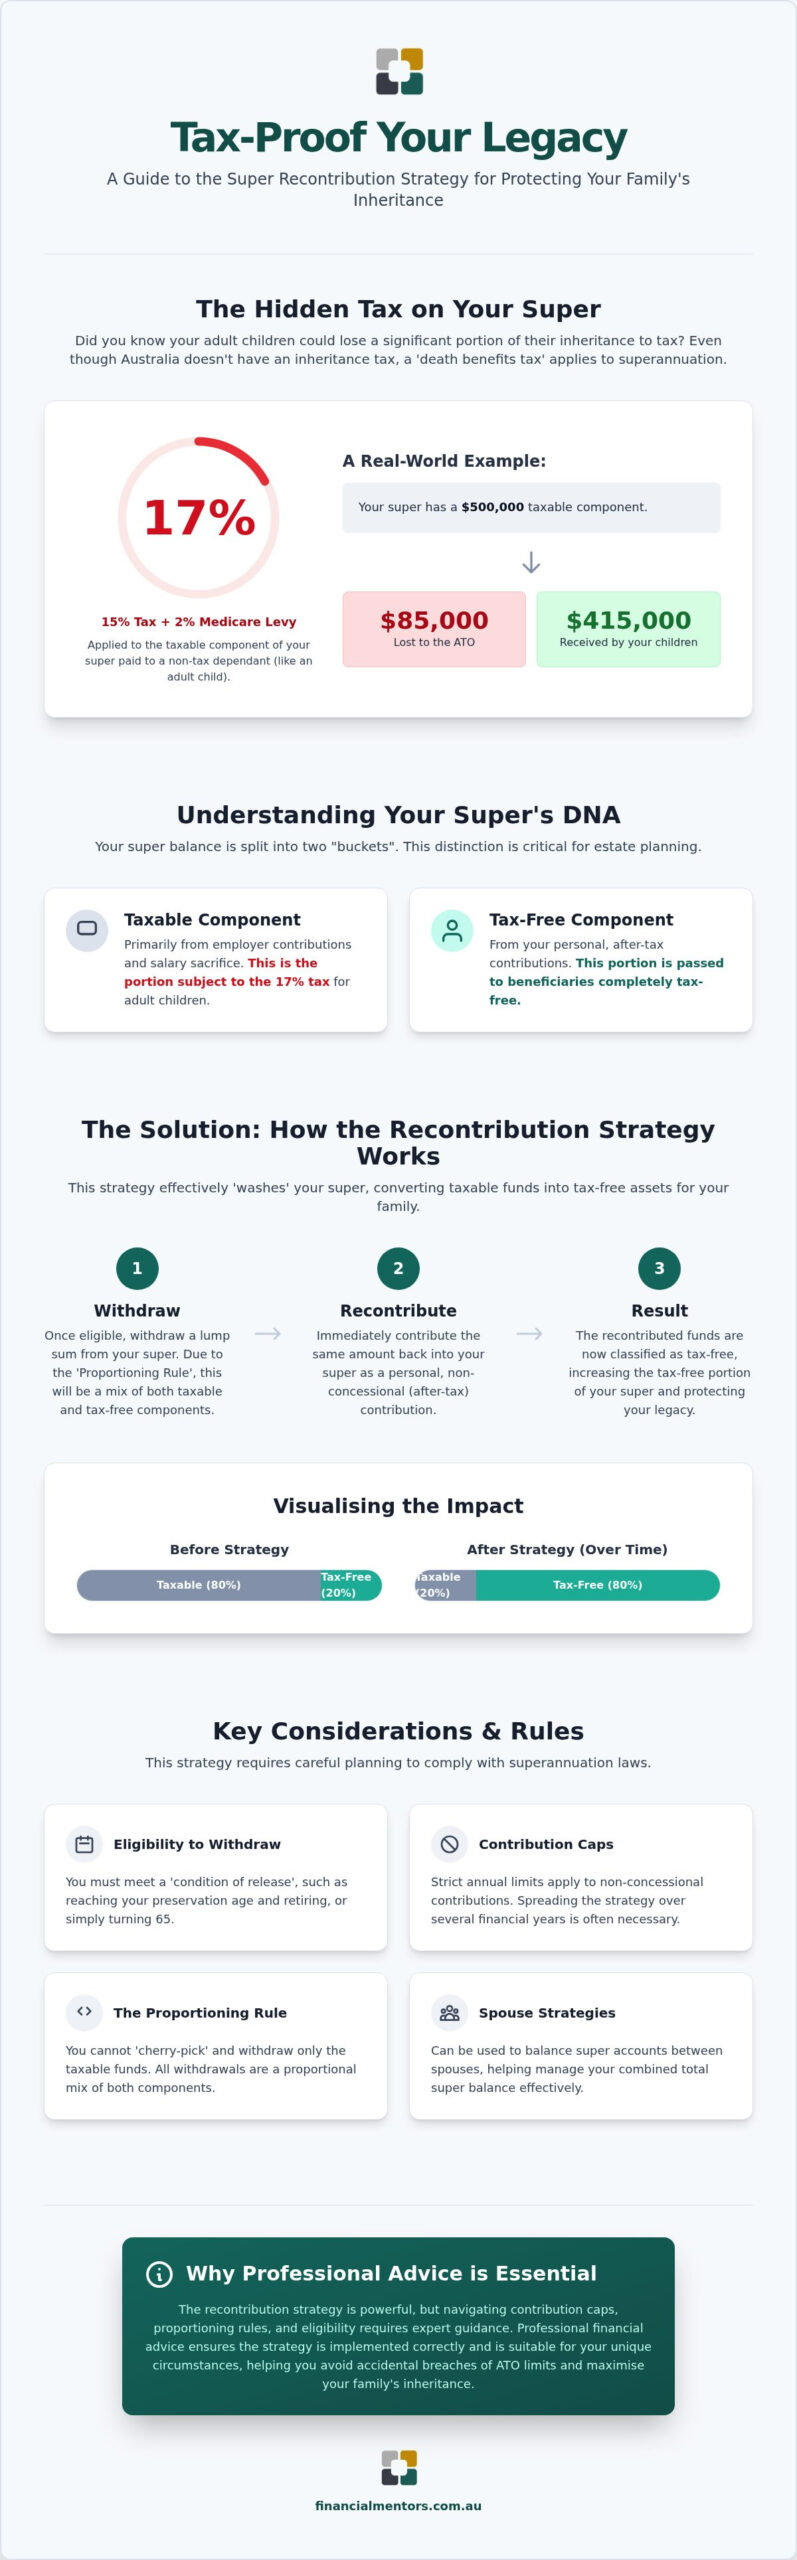
While you can generally enjoy tax-free withdrawals from your super after you turn 60 and retire, the rules change significantly when you pass away. Under the broad framework of Superannuation in Australia, your adult children are often classified as “non-tax dependants.” This means they don’t inherit your super with the same tax exemptions you enjoyed. Instead, they are required to pay a 15 per cent tax plus a 2 per cent Medicare Levy on the taxable component of the death benefit. Consider a scenario where your super contains a $500,000 taxable component. Without a plan, your children would be forced to hand over $85,000 to the ATO. It is a heavy price for them to pay for your lifetime of diligent saving.
If You Start Today: The Power of Proactive Planning
Viewing this as a long-term project rather than a one-off task helps you manage the process without stress. If you begin this journey early, you can often repeat the strategy over several years to gradually convert your entire balance. There is a deep sense of emotional relief that comes from knowing you’ve “tax-proofed” your legacy for your loved ones. You’ve done the heavy lifting so your children won’t have to. A recontribution strategy for super is a method to maximise the tax-free portion of a super interest for estate planning purposes. It ensures that more of your hard-earned wealth stays within the family, providing the stability and support you always intended for them.
Understanding the ‘Taxable’ and ‘Tax-Free’ Components of Your Super
Do you ever look at your super statement and wonder what those different “components” actually mean for your family? It is helpful to think of your super as being held in two separate internal buckets. The first is the Taxable bucket, which is usually built from your employer’s compulsory payments and any salary sacrifice you’ve chosen to make. The second is the Tax-Free bucket, which holds the money you’ve contributed from your own pocket after you’ve already paid income tax. Understanding these divisions is a key part of learning how super works, as it dictates how much the ATO might eventually claim from your estate.
The Proportioning Rule: Why You Cannot Cherry-Pick
If you were hoping to simply withdraw the taxable portion and leave the tax-free part alone, you’ll encounter a hurdle known as the Proportioning Rule. Imagine a jar filled with 80 red marbles representing your taxable funds and 20 blue marbles representing your tax-free funds. If you reach in and take a handful, you can’t choose to only pick the red ones; you’ll always get a mix that reflects the 80/20 ratio of the whole jar. Every withdrawal you make from super follows this same logic. This is exactly why a recontribution strategy for super requires such precise execution. You withdraw a proportional mix, but when you put that money back in as a non-concessional contribution, the entire amount lands in the tax-free bucket. Over time, repeated cycles can gradually “wash” the taxable component away. This level of detail is where expert tax return preparation becomes invaluable, ensuring every transaction is recorded correctly to avoid unwanted attention from the regulator.
Visualising the Shift: From Taxable to Tax-Free
What does this look like in practice? After you successfully complete a recontribution strategy for super, your next annual statement will show a tangible shift. The tax-free component will be higher, and the taxable portion will have shrunk. This isn’t just a temporary accounting trick. It’s a permanent change to the DNA of your retirement savings. Once money is classified as tax-free, it retains that status for the rest of your life and beyond. If you are feeling uncertain about how your current balance is split, a quick conversation about retirement planning can help you identify if your “buckets” are currently working in your family’s best interests.
Three Strategic Reasons to Consider a Recontribution Strategy
Why go through the effort of withdrawing and re-depositing your funds? While the tax savings for your children are a powerful motivator, a recontribution strategy for super offers broader benefits that can significantly improve your own lifestyle during retirement. This approach isn’t just about a single tax win; it’s a vital component of a planned retirement. By looking ahead, you can align your super balance with your personal goals and family needs. It is an act of stewardship that ensures your wealth is positioned exactly where it can do the most good.
The Centrelink Advantage: Maximising the Age Pension
One of the most effective uses of this strategy involves couples with an age gap. If your spouse is younger than the Age Pension age, any money held in their superannuation “accumulation phase” is generally not counted towards the Centrelink assets test. By withdrawing funds from the older partner’s account and recontributing them into the younger partner’s name, you might qualify for a higher Age Pension payment. This allows you to maximise your government entitlements while keeping your household wealth intact. This move requires a careful understanding of the bring-forward arrangement, which from July 1, 2026, allows eligible individuals to contribute up to $390,000 in a single year. You can find more details on these eligibility requirements in this in-depth guide to the recontribution strategy.
Spousal Equalisation and the Transfer Balance Cap
Another reason to consider this move is to manage the Transfer Balance Cap. From July 1, 2026, this cap increases to $2.1 million. This limit dictates how much you can move into a tax-free retirement pension. If one partner is approaching this limit while the other has plenty of room, a recontribution strategy for super allows you to equalise your balances. By shifting wealth to the spouse with a lower balance, you ensure that as much of your combined wealth as possible stays in the tax-free retirement phase. It is a sophisticated part of wealth creation strategies australia that protects your income from unnecessary tax and provides a better balance of assets between you and your partner.
Eligibility and Rules: Can You Implement This Strategy in 2026?
While the benefits of this approach are clear, the Australian superannuation system has strict “gatekeeper” rules that determine who can participate. You cannot simply move money in and out of your fund without meeting specific criteria. Before you begin, it is helpful to go through a checklist to see if a recontribution strategy for super is a viable option for your circumstances. Think of this as the foundation of your plan; getting these details right ensures your strategy is compliant and effective.
- Step 1: Check your age. The strategy is generally most effective for those between 60 and 75. Since the work test has been removed for non-concessional contributions for those under 75, this window has become a prime time for legacy planning.
- Step 2: Confirm your “Condition of Release”. You must be legally allowed to withdraw a lump sum from your super. This usually means reaching your preservation age and retiring, or turning 65.
- Step 3: Review your Total Super Balance (TSB). To make non-concessional contributions, your TSB must be below the relevant limit. As of July 1, 2026, the general Transfer Balance Cap rises to $2.1 million, which influences your contribution eligibility.
- Step 4: Understand the caps. You must stay within the non-concessional contribution limits to avoid heavy tax penalties.
- Step 5: Verify your Trust Deed. Not all super funds are the same. You must ensure your specific fund’s rules allow for the withdrawal and recontribution of funds in this manner.
The 2026 Contribution Caps and “Bring-Forward” Rules
For the 2026-27 financial year, the annual non-concessional contribution cap is $130,000. However, the “bring-forward” rule allows eligible individuals to contribute up to three years’ worth of caps in a single year. This means you could potentially recontribute up to $390,000 at once, provided your total super balance allows it. It is vital to get these numbers exactly right. Breaching these caps can lead to the ATO applying significant tax penalties, which can quickly undo the benefits of the strategy. If you’re feeling unsure about your current limits, seeking professional financial planning can provide the clarity you need to move forward with confidence.
Conditions of Release: Getting the Money Out First
The first hurdle is always access. You cannot recontribute what you cannot legally withdraw. For most Australians, the “magic” age is 65, where you gain full access to your super regardless of your employment status. If you are between 60 and 64, you must typically meet the definition of “retirement” by ceasing an employment arrangement. It’s also worth noting that Transition to Retirement (TTR) pensions have specific limitations. TTR accounts generally restrict lump sum withdrawals, which can make them unsuitable for a recontribution strategy for super unless you meet a full condition of release. Taking the time to verify your status now prevents complications later in the process.
Navigating the Complexity: Why Professional Advice is Essential
While the recontribution strategy for super sounds straightforward on paper, the practical application is a delicate balancing act. It isn’t just about moving money; it’s about ensuring every step adheres to strict legislative requirements. If you handle this poorly, you risk more than just a paperwork error. The ATO maintains a watchful eye on transactions that appear to be purely for tax avoidance, making the oversight of a dedicated wealth management office an essential safeguard for your family’s future. We believe that true stewardship involves protecting your wealth from unnecessary risks while you pursue your personal goals.
The Risk of DIY: Common Recontribution Pitfalls
Attempting this as a “do-it-yourself” project can lead to unintended consequences that outweigh the potential tax savings. One of the most frequent errors is accidentally breaching the non-concessional contribution cap. This often happens when a person forgets about other contributions made throughout the year, such as small personal payments or insurance premiums paid within the fund. Additionally, it is vital to maintain a buffer of “unrestricted non-preserved” funds. If you recontribute every spare dollar to maximise the tax-free component, you might find yourself short of cash for an unexpected emergency. Finally, the sequence of the “withdrawal and recontribution” must be documented with absolute precision. If the timing is off, or the paperwork is filed incorrectly, the ATO may not recognise the shift in your super’s components.
How Financial Mentors Can Guide You
At Financial Mentors, we act as your trusted guide through this compliance minefield. We provide personalised modelling that shows exactly how much tax your children could save, turning abstract rules into a clear, tangible financial benefit for your heirs. We also handle the coordination with your super fund, ensuring the transactions are seamless and correctly categorised for your future tax returns. This recontribution strategy for super doesn’t exist in a vacuum; it should be integrated with a retirement planning checklist australia for 2026. Our goal is to ensure your legacy is protected while keeping you on track for your broader life aspirations. We are here to partner with you, providing the steady, methodical oversight needed to give you genuine peace of mind as you enter this next chapter of life.
Securing Your Family’s Future Today
Taking control of your superannuation is one of the most significant acts of stewardship you can perform for your family. By understanding the distinction between taxable and tax-free components, you can ensure that more of your hard-earned wealth remains with your loved ones. We’ve explored how a recontribution strategy for super can effectively “tax-proof” your estate, balance your retirement income with your spouse, and even potentially improve your Age Pension outcomes. These aren’t just technical adjustments; they’re deliberate steps toward a more stable and certain future for your adult children.
While the rules for 2026 are complex, you don’t have to navigate them alone. Expert guidance ensures you stay within the contribution caps while maximising your strategic benefits. Book a consultation with Financial Mentors to see if a recontribution strategy is right for you. You can speak directly with Murray Frean, our primary Authorised Representative, about strategic legacy protection and expert superannuation compliance. Let’s work together to make sure your hard-earned savings are protected exactly as you intended for the next generation.
Frequently Asked Questions
Is a super recontribution strategy legal according to the ATO?
Yes, the Australian Taxation Office (ATO) recognises the recontribution strategy for super as a legitimate way to manage your retirement savings, provided you strictly follow the contribution caps and withdrawal rules. It isn’t a loophole, but rather a deliberate choice in how you structure your components. If the strategy is implemented within the law for genuine retirement or estate planning purposes, it’s a standard part of professional financial advice. Professional oversight ensures your strategy remains compliant.
How much tax can my children actually save with this strategy?
Your adult children can save up to 17 per cent in tax on the portion of your super you successfully convert to a tax-free component. This consists of a 15 per cent tax rate plus the 2 per cent Medicare Levy. For example, if you move $200,000 from the taxable bucket to the tax-free bucket, your heirs could avoid a $34,000 tax bill. This makes a tangible difference in the legacy you leave behind for your loved ones.
What is the maximum age I can perform a recontribution strategy?
You can generally perform this strategy until you turn 75, as the work test has been removed for non-concessional contributions for individuals in this age bracket. Once you reach 75, your ability to make personal contributions into superannuation becomes very limited. It’s often wise to start the process in your early 60s, giving you ample time to move funds across multiple financial years while staying within the annual 2026 contribution caps.
Can I use a recontribution strategy if I am still working?
Yes, you can implement this strategy while working, provided you have reached age 65 or have met another condition of release. At age 65, you gain full “unrestricted non-preserved” access to your super, regardless of your employment status. If you are between 60 and 64 and still working, you might be restricted by preservation rules, so it’s essential to check if your specific employment situation allows for a lump sum withdrawal before proceeding.
What happens if I accidentally go over my contribution caps?
If you accidentally breach your non-concessional contribution caps, the ATO will typically issue a determination and apply a higher tax rate to the excess amount. You’ll generally have the option to withdraw the excess and associated earnings to mitigate some of the penalty. However, repeated breaches or failing to act on an ATO notice can lead to significant financial costs. This is why careful tracking and professional tax return preparation are so vital during the process.
Do I need to have a Self-Managed Super Fund (SMSF) to do this?
No, you don’t need a Self-Managed Super Fund (SMSF) to execute this strategy. Most large industry and retail funds are equipped to handle these transactions, although their internal processes and trust deeds can vary. It’s important to contact your fund’s administrator beforehand to confirm they can track the taxable and tax-free components accurately. Whether you have an SMSF or a retail fund, the underlying tax laws and contribution limits remain the same for everyone.
Can I recontribute money into my spouse’s super account instead of my own?
Yes, recontributing funds into your spouse’s account is a common and effective variation of a recontribution strategy for super. This is often used for “spousal balancing” to ensure both partners stay under the $2.1 million Transfer Balance Cap or to move wealth to a younger partner for Age Pension purposes. It is a practical way to manage your household’s total super balance while protecting your collective legacy. Just ensure your spouse is also eligible to make contributions.
Will this strategy affect my current Age Pension payments?
This strategy can actually increase your Age Pension payments if you move funds to a spouse who is younger than the Age Pension age. Money held in the accumulation phase for a younger spouse is generally not counted in the Centrelink assets test. By shifting funds from an older partner’s account to a younger partner’s super, your assessable assets decrease, which may lead to higher fortnightly payments. It’s a clever way to optimise your government entitlements during retirement.