

What if the greatest risk to your retirement isn’t a market downturn, but the quiet fear that your savings might run out before you do? It’s a common concern for many Australians, especially when faced with the complex web of Centrelink asset limits and the tax implications of superannuation withdrawals. You’ve worked hard to build your nest egg, and it’s only natural to feel protective of it. Understanding the various retirement income streams australia offers is the first step toward replacing that uncertainty with a sense of quiet confidence.
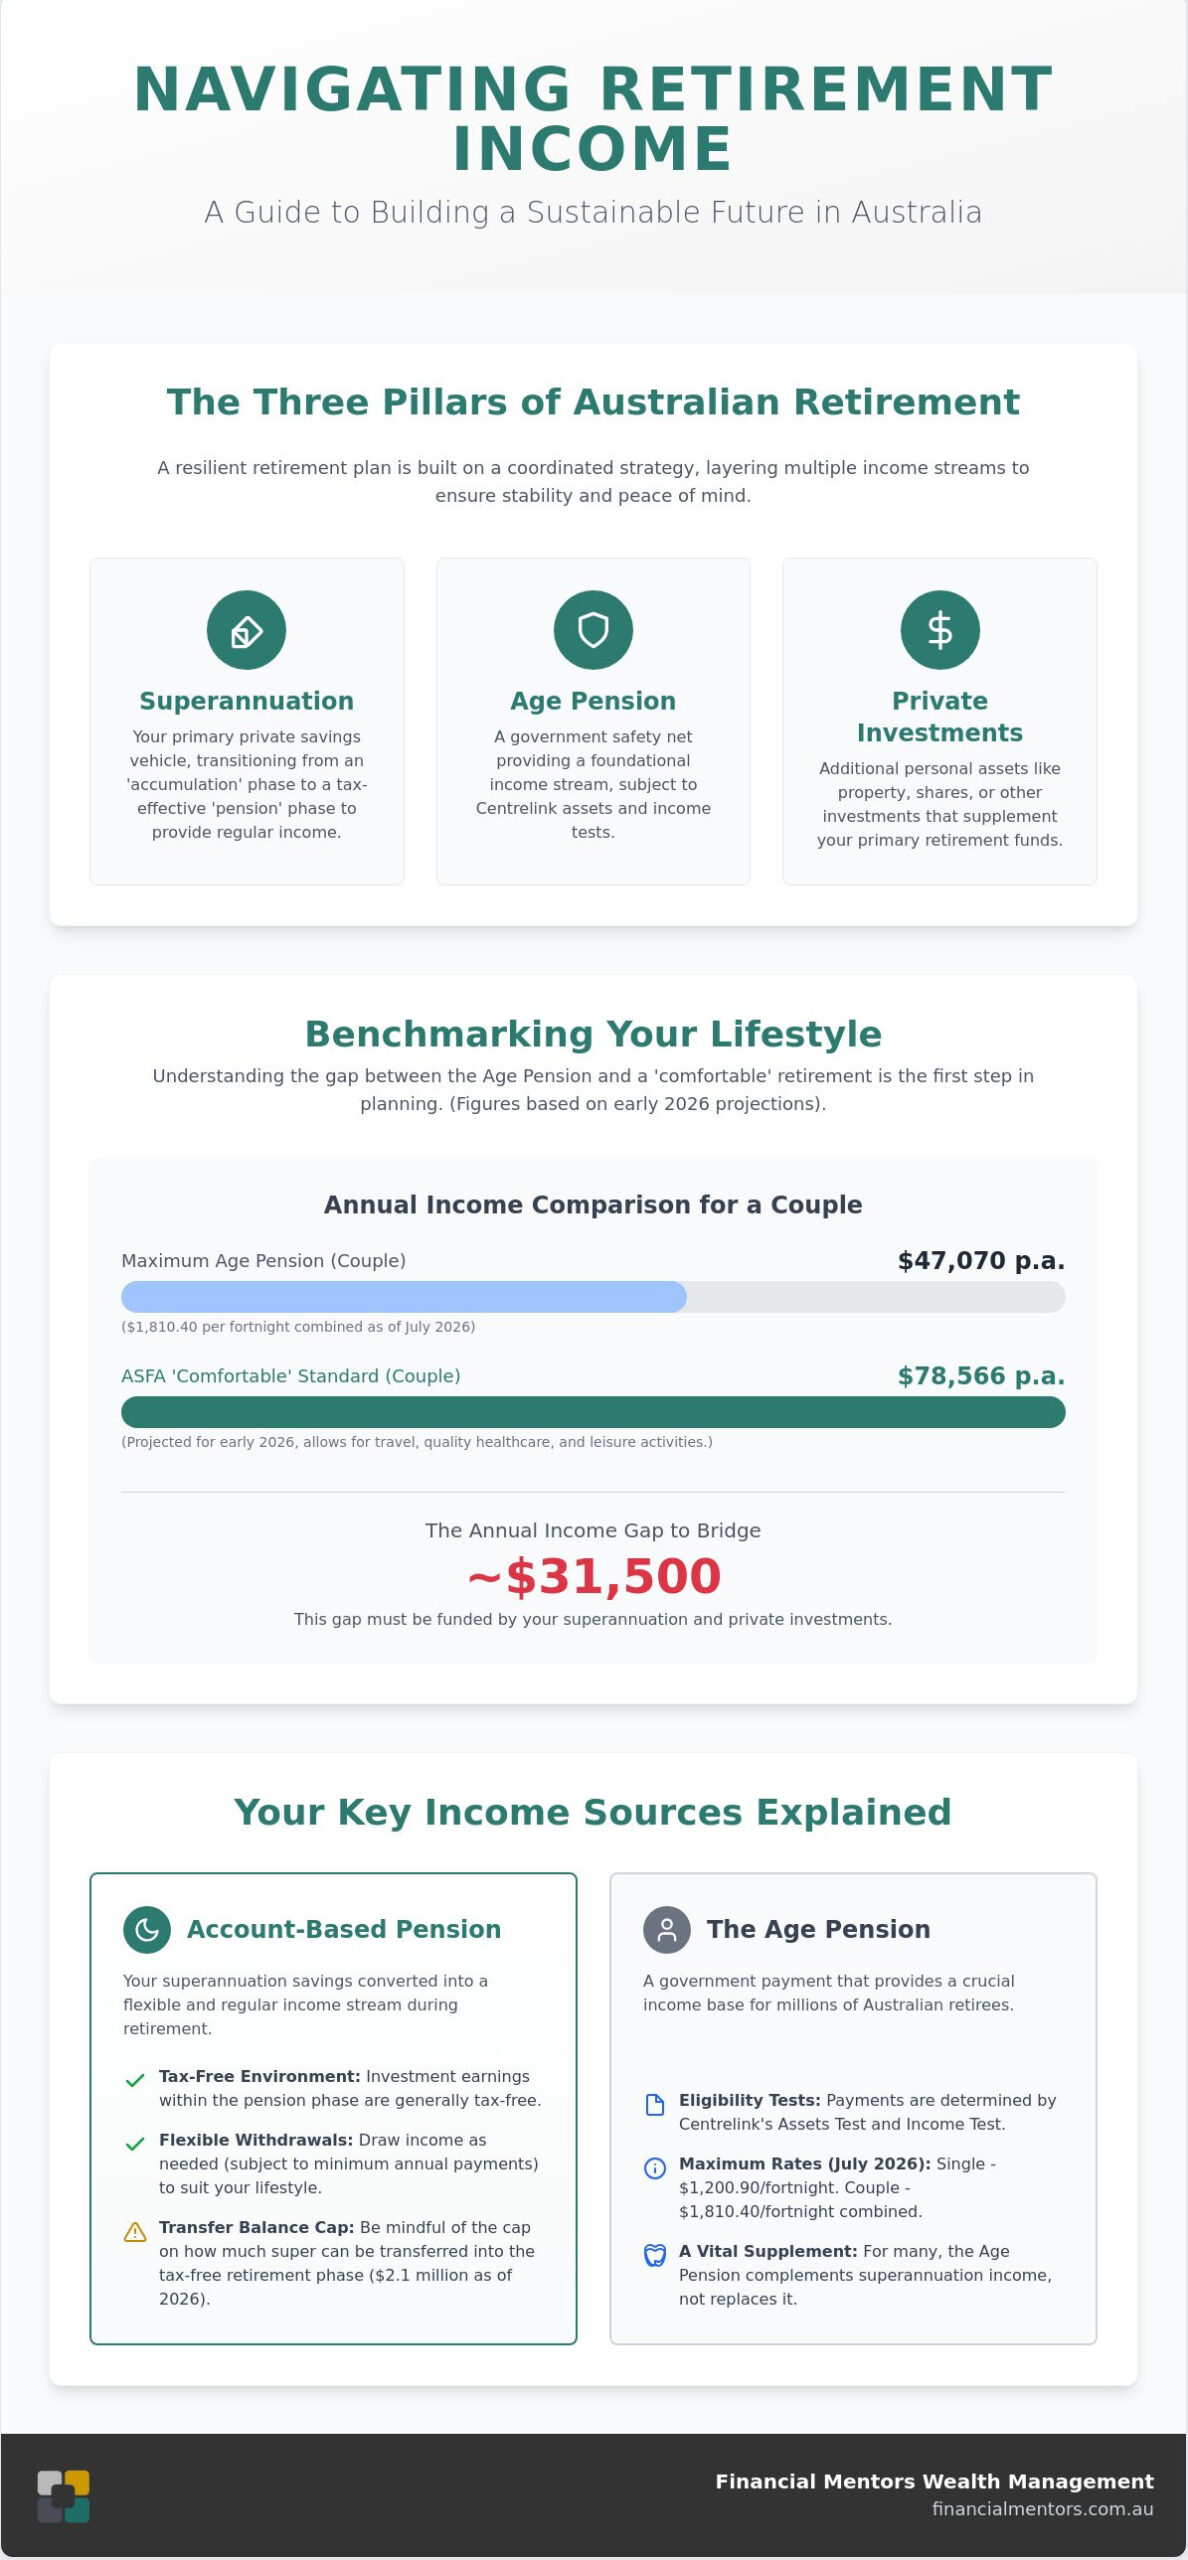
We believe that your post-work years should be defined by freedom rather than financial stress. With the ASFA comfortable standard for couples reaching $78,566 per year in early 2026, having a clear strategy is essential. In this guide, we’ll show you how to coordinate different income sources to ensure a stable, tax-effective, and comfortable lifestyle. We’ll explore the different income buckets available, including the Age Pension and superannuation, and explain how a strategic approach can help you maximise government entitlements while minimising your tax burden. By the end of this article, you’ll have a clear roadmap for a sustainable future that respects both your aspirations and your peace of mind.
Key Takeaways
- Understand how to transition from the accumulation phase to a pension phase, turning your hard-earned savings into a predictable series of regular payments.
- Learn how to layer the various retirement income streams australia offers, such as account-based pensions and the Age Pension, to create a reliable and sustainable financial safety net.
- Discover the 2026 ASFA Retirement Standard benchmarks to identify exactly what a “comfortable” lifestyle costs and how to plan for regular travel and quality healthcare.
- Identify strategic ways to optimise your income through professional tax preparation and estate planning, helping you protect your beneficiaries from the superannuation “death tax”.
- Find out how to reverse engineer your financial roadmap by starting with your lifestyle goals, ensuring your strategy is built around how you actually want to live.
What Are Retirement Income Streams in Australia?
Think of your retirement income as a steady flow rather than a stagnant pool. At its heart, a retirement income stream is simply a series of regular payments you receive from your superannuation or private investments once you stop working. In the context of retirement income streams australia, this usually means moving away from the accumulation phase, where you’ve spent decades building wealth, and entering the pension phase, where that wealth begins to serve you. This transition is a significant milestone that requires a shift in how you view your assets. Our national system is built on three sturdy pillars: Superannuation in Australia, the government Age Pension, and your own private savings or assets. Having the flexibility to choose how these streams flow is what allows you to tailor your retirement to the specific lifestyle you’ve envisioned for yourself.
The Transition from Saving to Spending
For many of our clients, the hardest part of retiring isn’t the lack of work. It’s the emotional shift of no longer seeing a traditional salary hit the bank account every fortnight. It can feel unsettling to watch your account balances fluctuate while you’re drawing from them. This period is also where you face sequencing risk, which is the danger that a market dip early in your retirement could have a lasting impact on your total savings. To manage this, we often look toward the pension phase of super. It’s a highly tax-effective vehicle that allows you to draw a regular income while keeping the remaining balance invested in a tax-free environment, helping your money work harder for longer.
Why a Single Stream is Rarely Enough
While the Age Pension provides a vital safety net for more than half of Australian retirees, relying on it alone often leads to a modest lifestyle rather than the comfortable one many hope for. If you want the freedom to travel, dine out, or maintain top-level private health cover, you’ll likely need to layer your income. Think of your different assets as a coordinated team working together. One stream might provide the baseline for your groceries and bills, while another helps fund your hobbies or occasional home improvements. By layering your retirement income streams australia, you create a more stable and resilient financial foundation that can grow alongside your changing needs and provide the peace of mind you deserve.
Primary Sources of Retirement Income: Exploring Your Options
Choosing the right mix of retirement income streams australia offers is much like assembling a puzzle where every piece needs to fit your unique lifestyle perfectly. While superannuation is often the primary engine of your post-work finances, a truly resilient plan usually involves a combination of sources. This layering approach allows you to balance growth with security, ensuring you have enough for the daily essentials while still being able to fund those “bucket list” experiences. Whether it’s the reliability of the Age Pension or the flexibility of an account-based pension, understanding how these options interact is the key to a sustainable future.
Account-Based Pensions vs. Transition to Retirement (TTR)
For most Australians, an account-based pension is the most straightforward way to turn super savings into a regular “paycheck”. Once you reach your preservation age and meet a condition of release, you can move your super into the pension phase. The major benefit here is that the earnings within the fund are generally tax-free. However, it’s vital to keep an eye on the transfer balance cap, which sits at $2.1 million as of 2026. If you’re still working but want to start topping up your income, a Transition to Retirement (TTR) strategy might be more suitable. This allows you to access a portion of your super while you’re still in the workforce, helping you ease into retirement without a sudden drop in your standard of living.
The Role of the Age Pension and Centrelink
The Age Pension remains a cornerstone of the Australian retirement system, serving as either a primary income source or a helpful supplement. As of July 2026, the maximum rate for a single person is $1,200.90 per fortnight, while couples can receive up to $1,810.40 combined. Eligibility is determined by Centrelink through two main tests: the Assets Test and the Income Test. Even if you only qualify for a partial payment, the benefits are significant. Holding a Pensioner Concession Card can lead to substantial savings on medicine, utility bills, and rates, which helps your other savings go much further. If you aren’t sure where you stand with these thresholds, our specialists can provide retirement planning advice to help you structure your affairs effectively.
Beyond super and the pension, you might also consider annuities for guaranteed income that isn’t tied to share market performance. Alternatively, private investments like dividend-paying shares or rental properties can provide an extra layer of growth. To see how these figures stack up against national benchmarks, you can check the latest ASFA Retirement Standard to ensure your projected income aligns with a comfortable lifestyle. By coordinating these different sources, you can build a strategy that feels both practical and wise.
Benchmarking Your Lifestyle: Modest vs. Comfortable in 2026
If you’ve ever wondered how your savings will translate into real-world lifestyle choices, you aren’t alone. Most Australians find it helpful to have a clear target to aim for, and that’s where the ASFA Retirement Standard comes in. This national benchmark is updated quarterly to reflect the actual cost of living for retirees across the country. When planning your retirement income streams australia, these figures serve as a vital reality check, helping you bridge the gap between your current balance and your future aspirations. It’s important to remember that these estimates assume you own your home outright, as rent or mortgage payments can significantly alter the required budget.
A “comfortable” retirement in 2026 is defined by more than just meeting the essentials. It includes the ability to maintain top-level private health insurance, upgrade household appliances when needed, and enjoy regular dining out. For those who split their time between countries or have international coverage needs, specialised firms like The Modern Medicare Agency offer insights into navigating complex insurance landscapes. It also accounts for the freedom to travel, whether that’s a trip to see family interstate or an annual overseas holiday. On the other hand, a “modest” lifestyle covers the basics like home repairs and a reliable car, but it leaves much less room for leisure or luxury. Choosing which path you want to take is the first step in deciding how to structure your income.
2026 Expenditure Estimates for Australian Households
According to the latest data from the March quarter of 2026, a single person now needs approximately $55,923 per year to maintain a comfortable lifestyle. For couples, that figure rises to $78,566 annually. If you’re aiming for these targets, the estimated lump sum required at retirement is roughly $630,000 for singles and $730,000 for couples, assuming you also receive a partial Age Pension. Building a solid base today is key to meeting these targets, as we discuss in our guide on building the foundation for your future. Knowing these numbers allows you to work backward from your desired lifestyle to your current savings strategy.
Adjusting for Inflation and Cost of Living
One of the biggest challenges in retirement planning is that the cost of a “comfortable” life doesn’t stay still. Recent inflationary pressures have seen these benchmarks rise steadily, meaning a static savings goal you set five years ago might no longer be enough for a 30-year retirement. This is why we focus on creating “real” income streams, which are strategies designed to grow or adjust over time to maintain your purchasing power. If your income doesn’t keep pace with the rising price of groceries, fuel, and healthcare, your standard of living could slowly erode. By preparing for these shifts now, you can ensure your retirement income streams australia remain robust enough to support you for the long haul.
Optimising Your Income: Tax Strategy and Estate Planning
Generating a steady flow of funds is only one half of a successful strategy. The other half is ensuring that your retirement income streams australia are structured to be as tax-efficient as possible. Many retirees mistakenly believe that once they stop working, their relationship with the ATO becomes simple. In reality, a coordinated approach between wealth management and accounting can reveal significant opportunities to keep more of your money. It’s about the principle of stewardship; we want to ensure that the way you fund your life today doesn’t unintentionally compromise the legacy you wish to leave for the next generation.
Professional tax return preparation is a vital part of this process. It’s not just about compliance, but about identifying missed opportunities for offsets and rebates that are specifically designed for seniors. When your tax strategy and retirement plan work in harmony, you gain the peace of mind that comes from knowing your financial house is in order and your future is well-protected.
Tax-Effective Withdrawals and the 60+ Advantage
If you’ve reached age 60, you’ve likely unlocked one of the most significant benefits of the Australian system: tax-free superannuation withdrawals. For the majority, this means every dollar drawn from your account-based pension arrives in your bank account without the ATO taking a slice. However, if you’ve worked in the public sector or hold “untaxed” components in your fund, the rules can change. If you fall into this category, then specific tax rules may apply to your payments. This is where professional guidance becomes invaluable, ensuring you don’t accidentally trigger an unnecessary tax bill through an incorrectly structured withdrawal.
Estate Planning: Protecting the Remaining Capital
A truly wise retirement strategy always looks beyond the immediate horizon. While your income streams support your life today, there is often a hidden “death tax” waiting for your beneficiaries if your super is left to adult children who are no longer financially dependent. This tax can be as high as 15% plus the Medicare levy on the taxable component of your balance. By using tools like Binding Death Benefit Nominations (BDBN), you can specify exactly who receives your remaining capital and how. Our estate planning advice helps you navigate these rules so that your hard-earned wealth is preserved for your loved ones rather than being eroded by avoidable taxes.
If you’re ready to see how a coordinated strategy can protect your income and your legacy, we invite you to reach out to our team for personalised retirement planning that puts your goals first.
Designing Your Personalised Income Roadmap with Financial Mentors
Building a secure future is rarely about finding a single “magic” product. Instead, it’s about how you coordinate the various retirement income streams australia makes available to you. While the data and thresholds we’ve discussed might feel overwhelming, they are simply the raw materials for your plan. Our role is to act as the guide that helps you turn this complex information into a simple, actionable roadmap. We believe in “reverse engineering” your retirement; we start by asking what your ideal Tuesday looks like, then we build the financial structure necessary to fund it.
This approach moves the focus from abstract numbers to your actual life. If you know that your basic costs are covered by a combination of the Age Pension and an account-based pension, you can then decide how to use your remaining assets for the things that truly matter. Whether it’s helping grandchildren with their education or finally taking that long-awaited trip around the Kimberley, your plan should be a reflection of your values. Regular reviews and professional stewardship ensure that as the world changes, your strategy remains aligned with your goals.
The Value of a Wise Mentor in Retirement
In an era of “DIY” finance, it’s tempting to try and manage everything yourself. However, the security that comes from professional, licensed advice is hard to replicate. Since 2003, we’ve helped Australians navigate multiple market cycles, regulatory shifts, and life transitions. We see our job as organising the “financial noise” into a clear, calm strategy. This partnership reduces the stress of decision-making, allowing you to focus on enjoying the time you’ve worked so hard to earn. When you have a trusted partner sitting across the table, the complexity of retirement income streams australia becomes a manageable path rather than a source of confusion.
Next Steps for Your 2026 Retirement Plan
If you’re ready to move from uncertainty to clarity, the first step is a simple conversation. We can help you assess your current assets against the 2026 benchmarks we’ve explored, identifying any gaps or opportunities for better tax efficiency. To make the most of our time together, it’s helpful to gather a few key items before we meet:
- Your most recent superannuation statements
- A summary of any private investments or bank balances
- Details of any outstanding debts or mortgages
- A rough estimate of your current annual living expenses
- Any existing estate planning documents or Wills
Your retirement is a major life transition, and it deserves careful, personalised attention. If you’re looking for a partner who is deeply invested in your long-term well-being, we invite you to organise a consultation with Financial Mentors to secure your income stream and begin your journey toward a more organised financial future.
Embracing the Freedom of a Secure Retirement
Choosing how to coordinate your retirement income streams australia is about more than just financial survival. It’s about the freedom to enjoy your morning coffee without worry and the ability to say “yes” to the experiences that matter most. We’ve explored how layering superannuation with the Age Pension and private assets can help you reach the 2026 comfortable lifestyle standards. When you combine this with a robust tax and estate strategy, you create a resilient foundation that protects both your current lifestyle and your future legacy.
Since 2003, our AFSL licensed advisors have focused on the expert integration of tax and wealth strategies to provide a steady, calm path forward. We believe in a warm, human-centric approach that treats you as a partner rather than a number. If you’re ready to replace the complexity of retirement with a clear, actionable roadmap, we’re here to help you navigate the transition with ease. You’ve worked hard for your savings; now it’s time to let them work hard for you.
Secure your retirement future with a personalised income strategy from Financial Mentors. Your best years are still ahead of you, and with the right plan in place, you can step into them with quiet confidence.
Frequently Asked Questions
What is the most tax-effective way to take an income from my super?
Transitioning your superannuation into an account-based pension after you reach age 60 is generally the most tax-effective strategy. For most Australians, both the regular income payments you receive and the investment earnings within the fund become tax-free at this stage. If you have a significant balance, it’s wise to consider how your withdrawals interact with your overall tax position to ensure you’re keeping as much of your hard-earned savings as possible.
Can I still get the Age Pension if I have an account-based pension?
Yes, you can receive the Age Pension while holding an account-based pension, provided you meet the Centrelink income and assets tests. Your pension balance is assessed as a financial asset under the assets test, and deeming rules are used to determine the income it’s expected to generate. If your total assets and income fall below the government thresholds, you may qualify for a full or partial payment to supplement your private savings.
How much money do I need for a “comfortable” retirement in Australia in 2026?
To achieve a comfortable lifestyle in 2026, the ASFA Retirement Standard suggests you’ll need an annual budget of roughly $55,923 for singles or $78,566 for couples. These benchmarks assume you own your home outright and will receive a partial Age Pension. In terms of a lump sum, this typically translates to needing about $630,000 for a single person or $730,000 for a couple by the time you stop working.
What is the difference between an annuity and an account-based pension?
An annuity provides a guaranteed income for a fixed term or for life, whereas an account-based pension is a flexible investment account that pays you an income from your super. While an annuity offers protection against market volatility and the risk of outliving your money, an account-based pension allows you to choose your investment strategy and access lump sums. Many retirees choose to layer both options to balance security with growth.
Is my retirement income affected by the transfer balance cap?
The transfer balance cap limits the total amount of super you can move into a tax-free retirement account, with the limit sitting at $2.1 million as of 2026. If your balance exceeds this cap, the excess must remain in an accumulation account where earnings are taxed at 15%. This cap is a vital consideration when structuring retirement income streams australia, as it ensures you remain compliant while maximising your available tax exemptions.
How often should I review my retirement income strategy?
We recommend reviewing your retirement strategy at least once a year or whenever you experience a significant life change. Regular reviews allow you to adjust for shifts in inflation, market performance, or updates to government regulations like the March and September Age Pension indexation. Staying proactive ensures your income remains sustainable and that your plan continues to reflect your personal goals and the lifestyle you wish to maintain.
What happens to my retirement income stream when I pass away?
Your remaining pension balance can usually be paid to your nominated beneficiaries as either a lump sum or an ongoing income stream. If you have a valid Binding Death Benefit Nomination in place, the fund trustee is legally required to follow your instructions. It’s important to structure this carefully to manage potential tax implications for adult children, ensuring your legacy is passed on in the most efficient way possible.
Can I change the amount of income I receive from my super pension?
Yes, you have the flexibility to adjust your pension payments at any time, provided you meet the minimum annual withdrawal limits set by the government. These limits are based on your age and are calculated as a percentage of your account balance each July. If you find you need extra funds for a specific purpose, such as a holiday or home improvements, you can increase your regular payments or take an additional lump sum.