

What if the most effective way to grow your net worth isn’t by chasing risky returns, but by stopping the leaks in your current financial plan? Many Australians find that high personal income tax rates, such as the 37% bracket for earnings over $135,000, eat into their savings before they even have a chance to invest. It’s natural to feel a bit overwhelmed when you’re trying to figure out the best wealth creation strategies australia has to offer while the rules around superannuation and capital gains seem to be constantly shifting.
We understand that you want a clear path forward that doesn’t involve unnecessary risks or complex jargon. You deserve to feel confident that your hard-earned money is working as hard as you do. This guide will show you how to coordinate tax efficiency, superannuation, and investment growth to secure your financial future. We’ll walk through the latest 2026 tax brackets, the move to payday super, and how to prepare for the capital gains tax changes scheduled for 2027. By the end, you’ll have a manageable plan to help you keep more of your income and build the retirement you’ve always imagined.
Key Takeaways
- Understand the difference between simple saving and deliberate asset building to ensure your money maintains its purchasing power in an inflationary environment.
- Discover how to coordinate your superannuation and investment portfolios to implement effective wealth creation strategies australia wide.
- Learn how to distinguish between good and bad debt while using tax-efficient methods like negative gearing to support your long-term growth.
- Identify how to adapt your financial plan during major life transitions, such as starting a family or approaching retirement, through a process of careful stewardship.
- Gain peace of mind by understanding how a professional mentor can help you conduct a periodic review to keep your financial position secure.
What is Wealth Creation in the Australian Context?
Wealth creation is more than just a financial buzzword; it is the deliberate process of building a base of assets that provides long-term income and security. For many Australians, the distinction between saving and creating wealth is often blurred. While saving involves putting money aside for a rainy day, true wealth creation involves putting that money to work. In an environment where inflation can erode the purchasing power of your bank balance, simply holding cash may not be enough to meet your long-term goals. Effective wealth creation strategies australia wide focus on moving beyond cash to assets that have the potential to grow over time.
This journey is built on the foundation of financial stewardship, which is the practice of managing your resources with a focus on future milestones. Whether you are looking at starting a family or planning for a comfortable retirement, stewardship requires a disciplined approach to every dollar. Fortunately, Australia’s financial system is highly regulated to help protect your interests. Professional advisors operating under an Australian Financial Services Licence (AFSL) provide a framework of accountability, ensuring that the advice you receive is designed to support your unique financial position.
The Difference Between Income and Wealth
It is a common misconception that a high salary automatically equals wealth. You might earn a significant income, but if those funds are entirely consumed by lifestyle costs and financial commitments, your long-term security remains fragile. Wealth is built through the role of compounding returns, where your earnings generate their own earnings over decades in the Australian market. This process transforms your hard work into a self-sustaining engine. Wealth is the ability to sustain your lifestyle without active employment.
Why 2026 is a Significant Year for Australian Investors
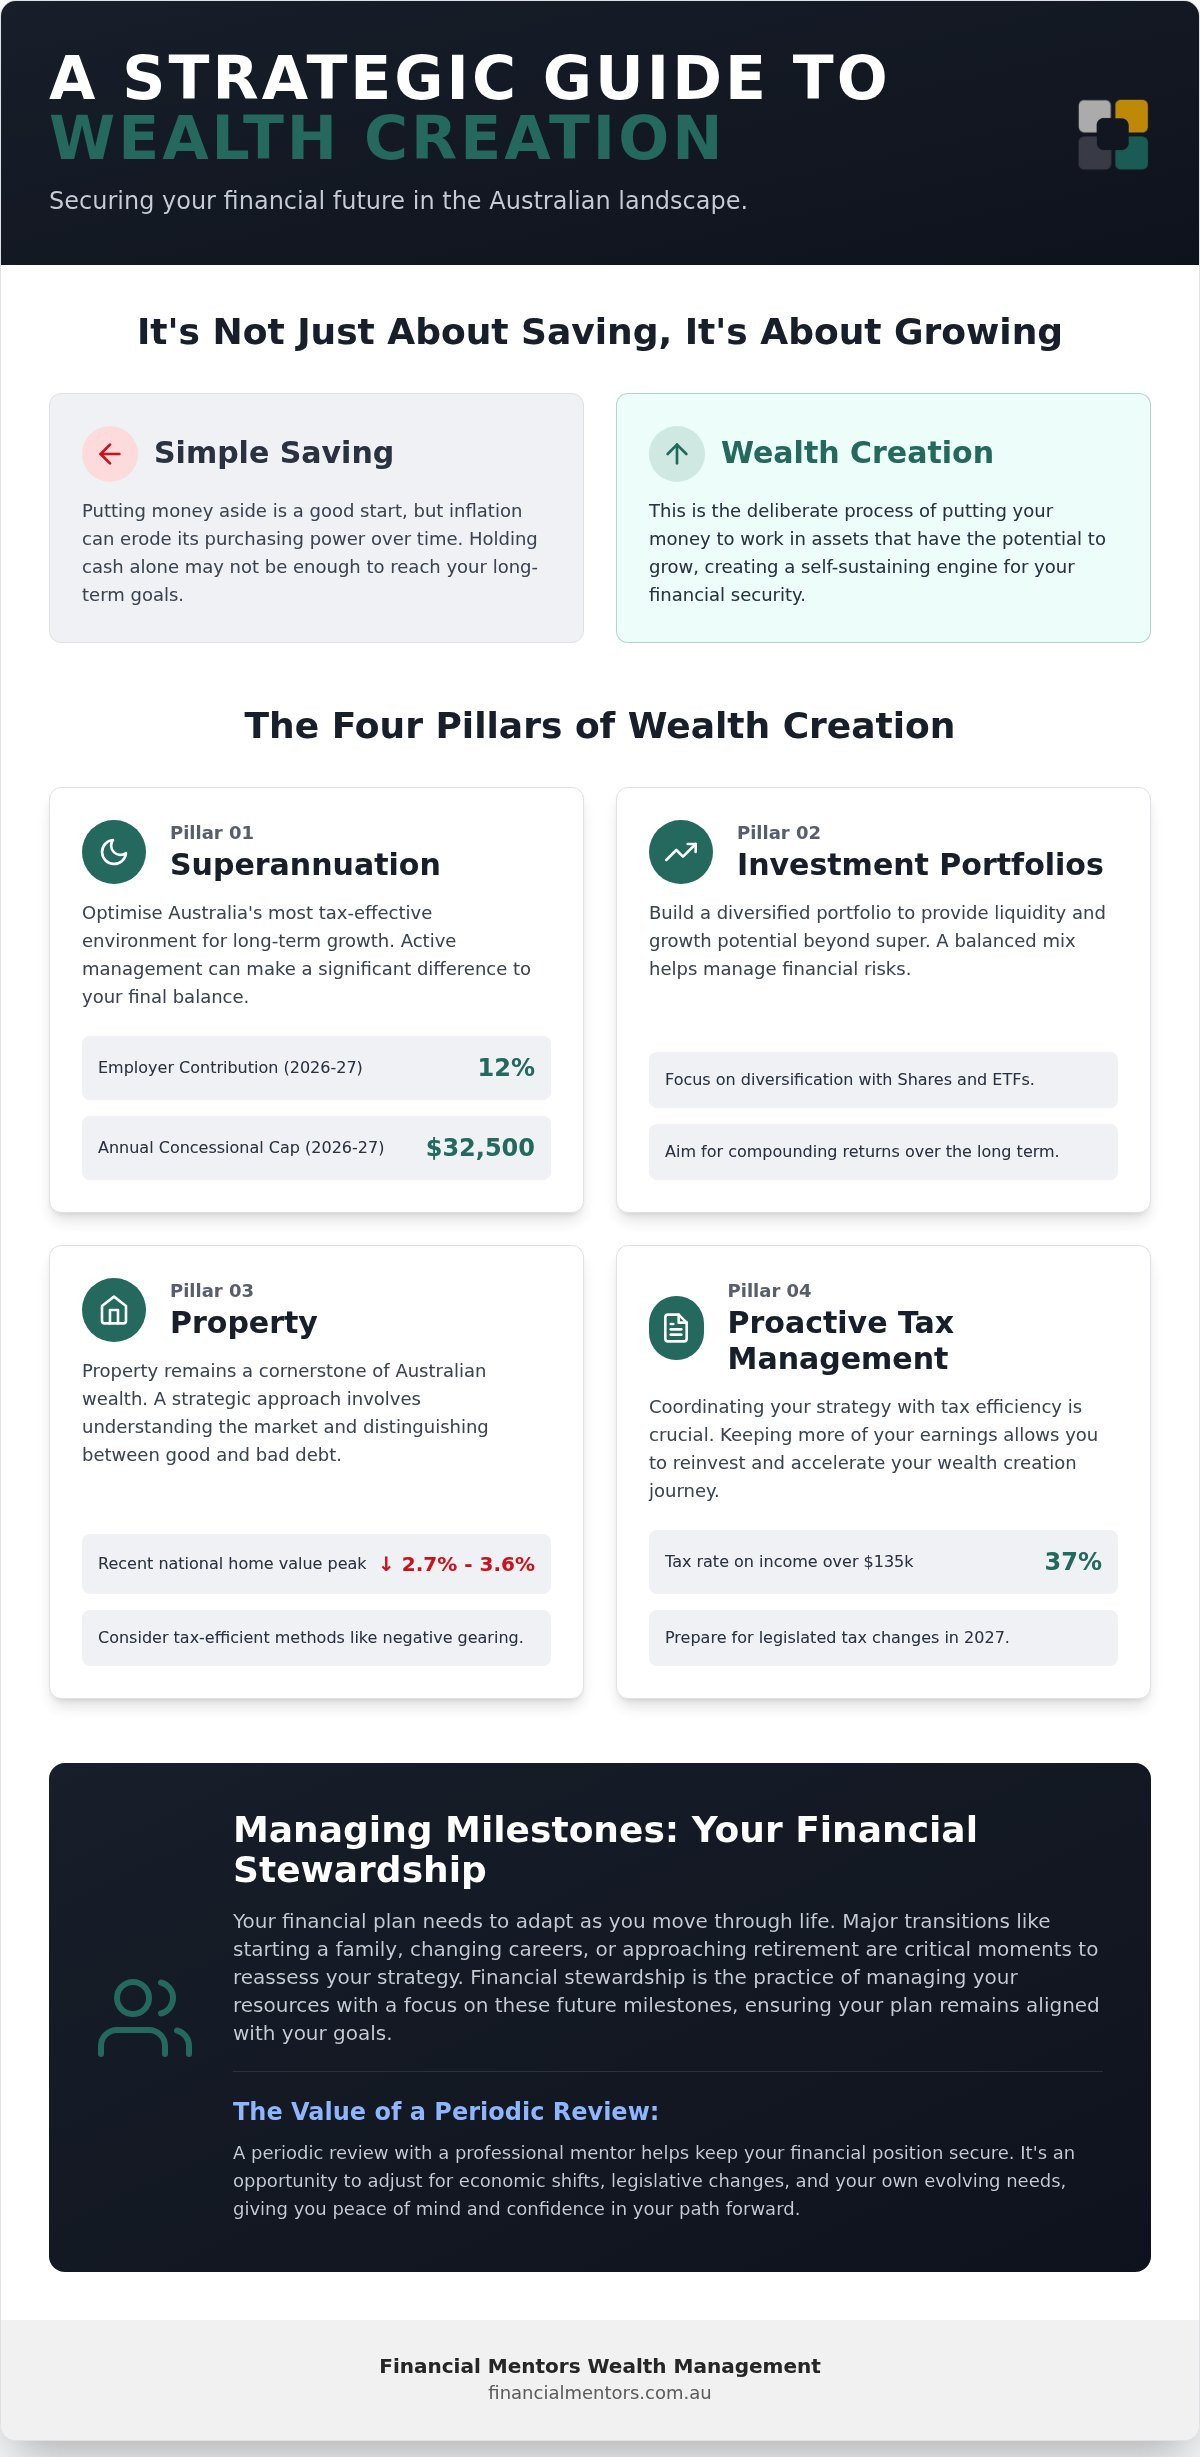
The current economic climate presents a unique set of challenges and opportunities. With national home values falling between 2.7% and 3.6% below the March 2026 peak, the traditional property model is being tested. Shifting interest rates, currently sitting at an official cash rate of 4.35%, mean that borrowing costs are higher, requiring a more calculated approach to debt. This volatility highlights the necessity of professional financial planning to help you stay on track. Moving into 2027, legislated tax changes will further alter the landscape, making it the perfect time to review your wealth creation strategies australia to ensure they remain fit for purpose.
The Four Pillars of Wealth Creation Strategies in Australia
Building a secure future isn’t about finding one “perfect” investment. It’s about coordinating different areas of your financial life so they work together. Most successful wealth creation strategies australia rely on four specific pillars: superannuation, investment portfolios, property, and proactive tax management. When these elements are aligned, they create a resilient foundation that can withstand economic shifts and support your lifestyle goals.
Superannuation remains the most tax-effective environment for long-term growth. With the employer contribution rate at 12% for the 2026-2027 financial year, your super is already working in the background. However, taking an active interest in how this money is managed can make a significant difference to your final balance. Alongside super, a diversified investment portfolio of shares and ETFs provides liquidity and growth potential. While property remains a favourite for many, integrating strategic tax return preparation allows you to keep more of your earnings to reinvest back into these assets.
Optimising Your Superannuation
Understanding your contribution options is a practical first step. Concessional contributions are made before-tax, such as salary sacrifice, and are capped at $32,500 per year for 2026-2027. Non-concessional contributions are made from your after-tax income. If you have multiple super accounts from previous jobs, consolidating them can reduce duplicate fees and make tracking your progress much easier. A planned retirement that feels secure starts with the small, intentional choices you make regarding your super today.
Property and Shares: Finding the Right Balance
Finding the right mix between property and shares depends on your individual goals and timeframe. Shares and ETFs generally offer higher liquidity, allowing you to access funds relatively quickly if your circumstances change. Residential property offers a sense of stability, though it requires a larger upfront commitment and can be harder to sell in a hurry. Developing balanced wealth creation strategies australia requires looking at both the growth potential of the stock market and the long-term stability of bricks and mortar. To avoid concentration risk, it’s wise to avoid putting all your assets into a single class. If you have significant equity in your home, you might consider how to use it strategically without over-leveraging your future. If you would like to explore how these pillars apply to your specific life stage, you can start by booking an initial appointment to discuss your options.
Tax Efficiency and Debt: The Engines of Strategic Growth
Debt is often viewed as something to avoid, but in the context of wealth creation strategies australia, it can be a powerful tool when managed with care. If you use borrowed funds to acquire assets that grow in value or produce income, you are using “good debt” to build your future. This is a core component of what a professional wealth management office helps you navigate. By understanding how to balance borrowing with your overall financial position, you can accelerate your progress toward long-term goals.
The Australian tax system provides several mechanisms that reward disciplined investors. Negative gearing, for instance, allows you to offset investment expenses against your taxable income, which can be particularly useful for property investors during the early years of an investment. For those focusing on the share market, franking credits help avoid double taxation by providing a credit for the tax a company has already paid on its profits. These features make effective wealth creation strategies australia unique and highly effective for those who plan ahead.
Good Debt vs. Bad Debt: A Framework for Stewardship
The key difference between debt types lies in the outcome of the spending. Bad debt usually involves high-interest consumer spending on items that lose value, like credit cards or car loans. Good debt acts as leverage, helping you grow your assets faster than you could using only your savings. Before taking on an investment loan, it is vital to assess your risk profile and ensure your cash flow can handle the financial commitments. Many investors choose interest-only structures for investment loans to maximise tax-deductible expenses, while others prefer principal and interest to build equity over time. For those interested in specialised property financing, visit Mortgage Suite Ltd.
In Australia, the tax system offers specific incentives for those who hold assets for the long term. Currently, resident individuals can benefit from a 50% Capital Gains Tax (CGT) discount on assets held for more than 12 months. This reward for patience is a cornerstone of strategic growth. Professional tax return preparation ensures you are claiming every legitimate deduction, such as interest expenses or property maintenance, while staying compliant with the latest ATO rulings. Every dollar you save through smart tax planning is essentially a guaranteed return on your investment.
Managing Milestones: Your Roadmap to Financial Stewardship
As your life evolves, your financial strategy must evolve with it. The wealth creation strategies australia you implement during your early career will likely look very different from those you need when you are starting a family or approaching retirement. Stewardship is about more than just accumulation; it’s about the careful management of your resources through every major transition. Conducting a periodic review of your financial position ensures that your investments remain aligned with your changing goals and risk tolerance. This level of oversight is why tax compliance and strategic planning are the foundation of any successful wealth management office.
Risk management is a vital part of this roadmap. Without adequate income protection or life cover, a sudden health issue could derail years of progress. Future-proofing your plan means preparing for financial adversity before it happens. Integrating estate planning advice early in the process ensures that the wealth you create is protected and eventually distributed according to your wishes. This coordination between growth and protection is what provides true peace of mind as you move through different life stages.
Building for the Next Generation
Effective estate planning is about much more than just drafting a Will. It involves strategic asset distribution to ensure your loved ones are looked after without facing unnecessary tax burdens. For instance, superannuation death benefits can have complex tax implications for adult beneficiaries who are not financial dependants. By planning ahead, you can manage how an inheritance is received, ensuring your legacy provides lasting stability for the next generation. It is about ensuring your hard work benefits your family in the most efficient way possible.
The Psychology of Long-Term Investing
Success in wealth creation often depends as much on your temperament as it does on your technical strategy. When markets become volatile, it is easy to let emotion drive your decisions or feel the urge to change course in response to headlines. A wise mentor knows that staying the course is usually more productive than trying to time the market. Emotional decision-making often leads to selling low and buying high, which can significantly impact your long-term goals. Having a documented financial plan gives you a steady reference point during periods of uncertainty. If you are ready to create a roadmap tailored to your life milestones, you can book an appointment with our team today to begin the process.
Why a Professional Mentor is Your Best Asset for Wealth Creation
Attempting to manage your own finances can feel like a full-time job. While DIY investing is more accessible than ever, it often lacks the strategic coordination needed to manage complex tax laws and shifting superannuation rules. A professional mentor provides the objective perspective you need to reduce the stress of decision-making. By operating under the Australian Financial Services Licence (AFSL) framework, firms like Financial Mentors Wealth Management offer a level of security and accountability that DIY methods simply cannot match. This partnership allows you to focus on your life while a trusted guide ensures your wealth creation strategies australia are working effectively in the background.
One of the greatest benefits of professional guidance is the integration of diverse financial elements. Instead of looking at your tax return, super fund, and investment portfolio as separate pieces, a mentor sees them as one cohesive engine. This holistic view is what helps you keep more of your income and build a stable future. For many professionals, this includes exploring salary packaging options via Novated Lease Quotes to reduce taxable income. It’s about moving from a reactive approach to a proactive one, where every financial decision is made with your long-term goals in mind.
Every Australian family has a unique story. Cookie-cutter strategies often fail because they don’t account for your specific aspirations or the nuances of your family dynamics. Whether you are planning for your children’s education or managing an inheritance, your plan needs to be as individual as you are. Murray Frean and our team act as authorised representatives for your interests, creating a tailored roadmap that evolves as you do. This isn’t a “set and forget” document but a living strategy that we refine together through a periodic review of your circumstances. We focus on stewardship, ensuring that your assets are managed wisely to protect your financial position through all of life’s transitions.
Taking the First Step Toward Your Future
It’s common to feel that you should wait for the “perfect” market conditions before starting. However, the cost of delay is often much higher than the impact of market fluctuations. Starting your wealth journey today allows the power of compounding to work in your favour for longer. When you book an appointment with us, you won’t find a high-pressure sales environment. Our process begins with listening and validation. We want to understand what keeps you up at night and what you hope to achieve. This initial meeting is Step 01 of our process, where we focus on your needs and begin building the foundation for a more secure 2026 and beyond. We are here to help you take that next step with confidence and clarity.
Securing Your Financial Future with Confidence
Building a secure future is a journey that requires patience, discipline, and the right partnership. You’ve seen how coordinating your superannuation, investment portfolios, and tax efficiency can transform your financial position. True stewardship means looking beyond simple savings to embrace proactive wealth creation strategies australia that reflect your personal values and life milestones. Whether you’re starting a family or planning for retirement, having a clear roadmap allows you to face economic shifts with quiet confidence.
At Financial Mentors Wealth Management, we’ve been providing professional advice under our AFSL licence since 2003. We believe in an empathetic, mentor-led approach that integrates tax expertise with strategic financial planning to ensure your plan is as unique as you are. You don’t have to navigate these complex decisions alone. We’re here to listen, validate your goals, and guide you through every transition with steady, professional support.
Start your journey with a tailored wealth strategy from Financial Mentors Wealth Management today. We’re here to help you take that next step toward the future you’ve always imagined.
Frequently Asked Questions
What are the best wealth creation strategies for beginners in Australia?
Beginners should focus on the basics of stewardship by managing cash flow and maximising superannuation. The 12% Super Guarantee is a powerful starting point for any professional. You might also look at low-cost exchange-traded funds that allow you to diversify with small amounts of money. Establishing these habits early helps you handle financial adversity later in life. It’s about building a foundation that grows steadily through the power of compounding returns.
How much money do I need to start a wealth creation plan?
You don’t need a large inheritance to begin your journey toward financial security. Many managed funds and share platforms allow you to start with as little as $500; some even offer regular savings plans for smaller amounts. The most important factor is the cost of delay rather than the initial sum. Starting today with a small, disciplined contribution is often more effective than waiting years to save a larger amount while missing out on growth.
Is property or the share market better for building wealth in Australia?
Both asset classes play vital roles in balanced wealth creation strategies australia. Property offers the benefit of leverage and a sense of stability, though it requires significant financial commitments and has lower liquidity. The share market provides easier access, lower entry costs, and higher liquidity. Often, the best approach involves a mix of both to avoid concentration risk and ensure your portfolio remains resilient during economic shifts or periods of property market cooling.
How does superannuation fit into a wealth creation strategy?
Superannuation is often the most tax-effective environment for your long-term goals. Contributions are generally taxed at a lower rate of 15%, which is significantly less than the higher marginal tax brackets many professionals face. By making concessional contributions up to the $32,500 annual cap, you can reduce your taxable income while building a substantial nest egg. It acts as a future-proof engine that supports your lifestyle once you eventually reach the qualifying age of 67.
Can I build wealth while still paying off my home mortgage?
You can certainly grow your assets while managing a mortgage by using smart debt structures. Strategies like debt recycling involve using the equity in your home to invest in income-producing assets, potentially turning non-deductible debt into tax-deductible debt. Alternatively, using an offset account allows you to reduce the interest paid on your home loan while keeping your capital accessible for future investment opportunities. This approach balances your current obligations with your aspirations for growth.
What is the role of tax planning in wealth management?
Tax planning is the practice of organising your finances to ensure you keep as much of your hard-earned income as possible. It involves using legitimate mechanisms like franking credits, salary packaging, and capital gains tax discounts to improve your overall financial position. Without a strategic tax plan, you may be missing out on returns that could be reinvested into your portfolio. It is a core part of wealth management that supports your stability and long-term security.
Is negative gearing still a viable wealth strategy in 2026?
Negative gearing remains a viable strategy in 2026 for those in higher tax brackets looking to build a property portfolio. While national home values have cooled recently, the ability to offset investment losses against your personal income can provide significant tax relief. This is particularly relevant if you are earning over $135,001 and facing a 37% tax rate. However, it is essential to ensure the underlying property has strong growth potential to make the strategy worthwhile.
How often should I review my financial roadmap with a mentor?
We generally recommend a periodic review of your financial plan at least once a year. This ensures your strategy remains aligned with your current life stage, especially if you are experiencing transitions like starting a family or changing careers. You should also book an appointment if there are major regulatory changes, such as the upcoming capital gains tax shifts in 2027. Regular dialogue with a mentor provides the objective perspective needed to keep your roadmap on track.