

Generating income from investments in retirement requires shifting from growth accumulation to an income-focused portfolio strategy that combines Australian superannuation tax concessions with reliable yields. You can structure your financial position to establish a steady money coming in (income stream) for your future. Seeking professional advice will help you take a step closer to achieving your long-term goals with confidence.
Key Takeaways: Generating income from investments in retirement requires transitioning your superannuation to the pension phase and balancing dividend-paying equities with a two-year cash buffer.
- Maintain a 2-year cash reserve to prevent selling growth assets during market downturns.
- Except when inflation is high, avoid over-allocating to cash as it erodes purchasing power.
- Utilize franked Australian shares to generate tax-effective cash flow through attached tax credits.
- The ABS 2023 report shows many Australians must adjust plans due to financial adversity.
Generating Income From Investments in Retirement: 3 Core Strategies
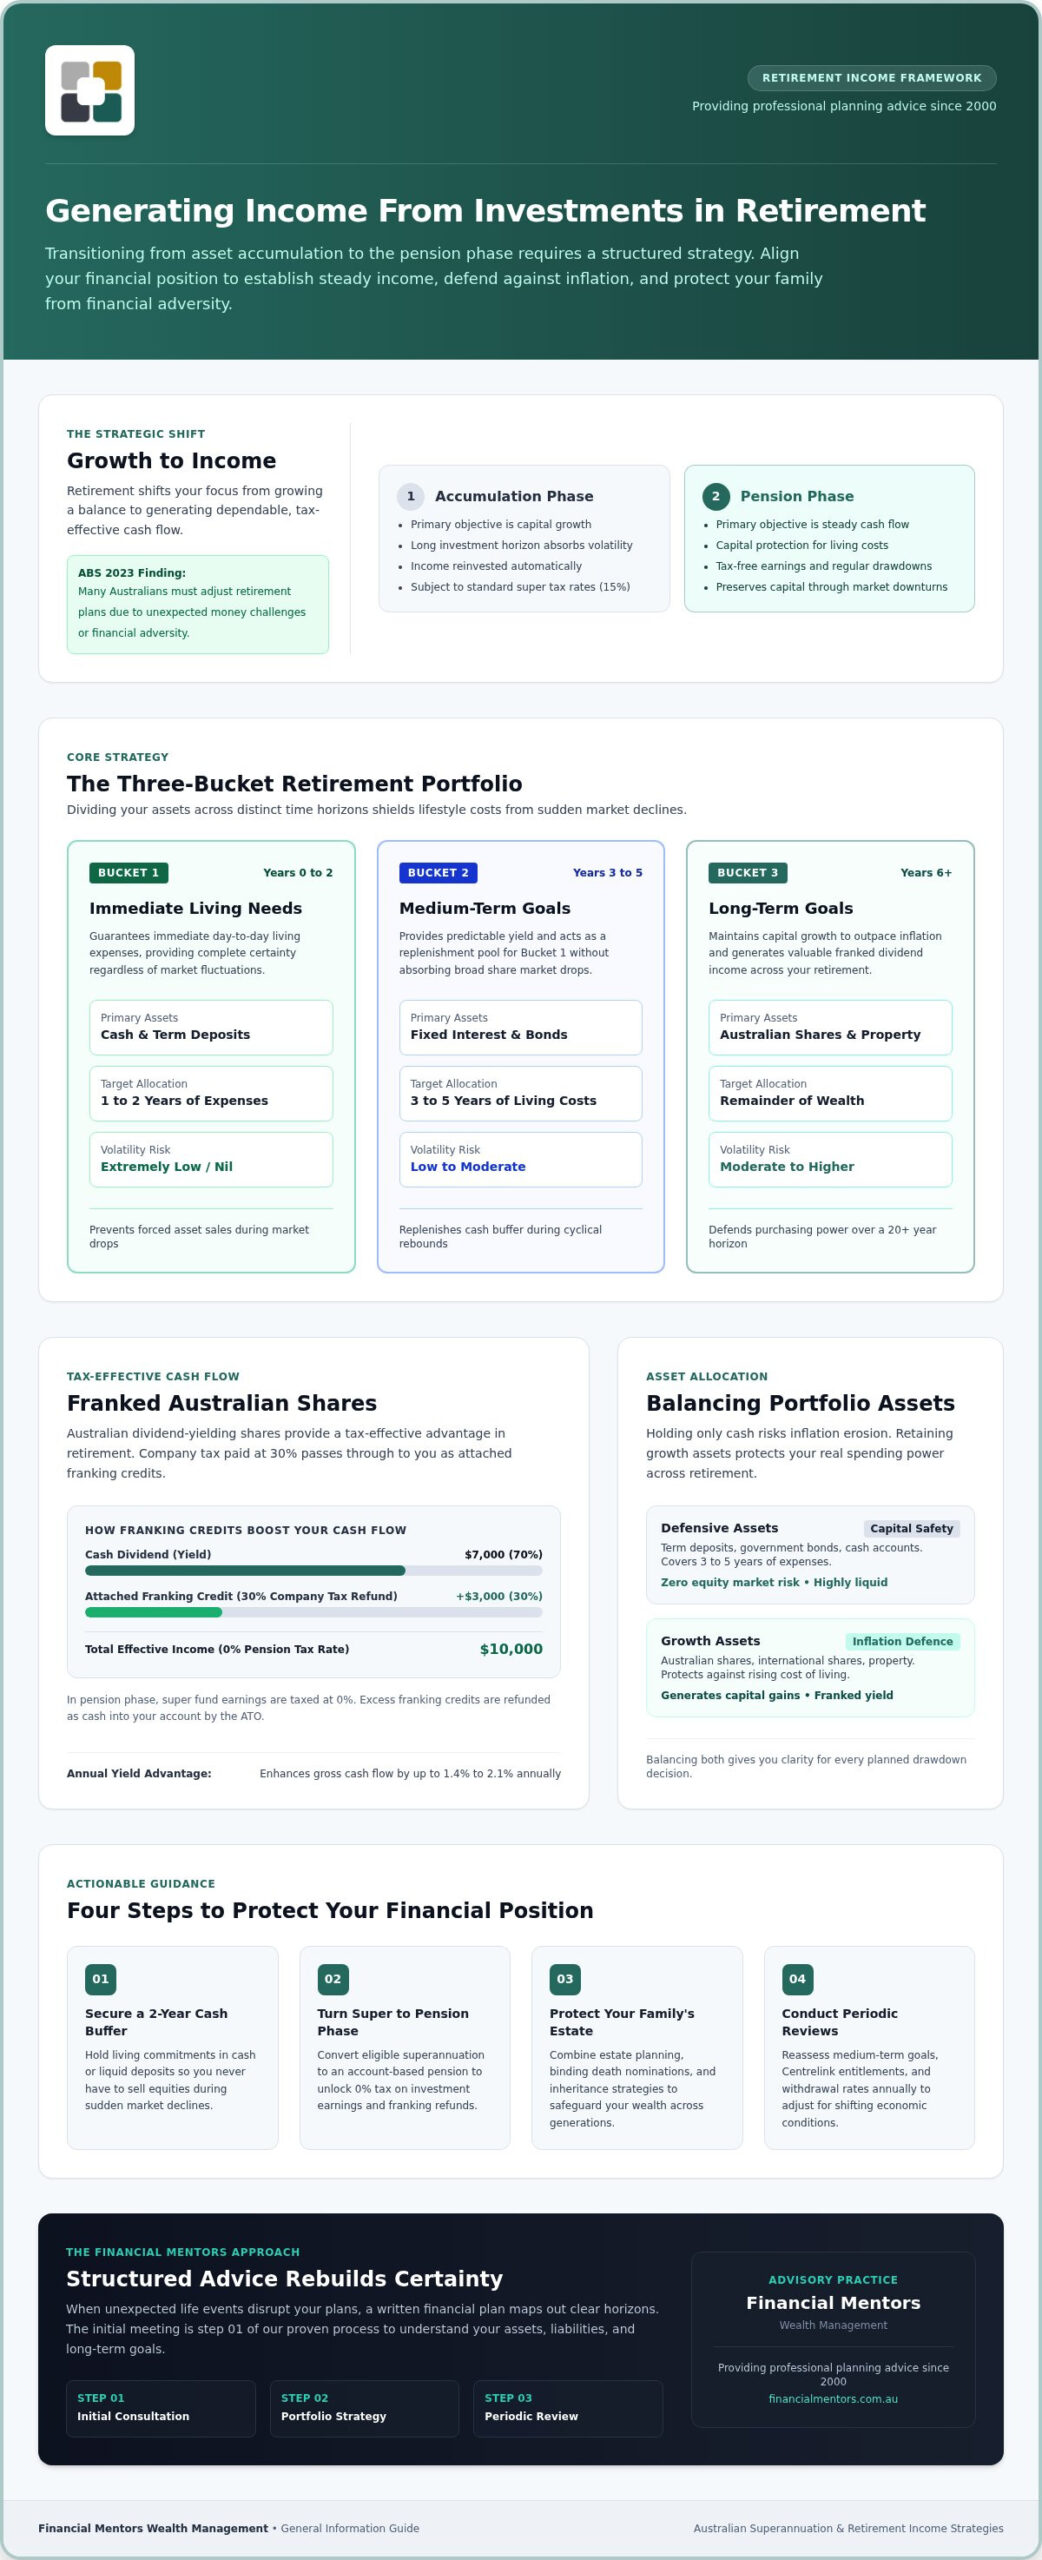
Dividing your wealth into clear buckets is the practical way to keep reliable money coming in during your later years. With clients we see that structuring investments into immediate needs, short-term reserves, and long-term goals reduces stress and shields your core lifestyle expenses from sudden market drops.
Before you choose a path, match your situation to a concrete step:
- If you have just left work and need cash for daily living, secure predictable payouts first (pension-phase income, term deposits, or defensive holdings).
- If you are five to ten years into retirement and worried about inflation, keep a measured slice of growth assets beside your income holdings so rising costs do not erode purchasing power.
- If a life event has unsettled your plans, pause new risk and rebuild around a written financial plan before you change product settings.
Building your financial plan around three distinct time horizons keeps those choices clear. First, secure your daily living costs with predictable payouts. Next, protect your medium-term goals with cash reserves. Finally, maintain growth assets to cover inflation over time.
You can arrange tailored guidance through our advisory team to match your current financial position. More on this: Financial Mentors Wealth Management.
Taking money out (pension phase) requires balancing growth with capital protection. Dividend-yielding shares fit people seeking growth, while annuity products suit retirees who value guaranteed certainty. Protecting your family against financial adversity takes careful planning: make a time to set the first step of your strategy.
Build an Income-Focused Portfolio That Pays You Regularly
Transitioning to retirement means shifting your strategy from accumulating assets to creating steady money coming in.
When leaving work or facing personal change, that shift can feel daunting. Data from the ABS 2023 Retirement Intentions release shows many Australians adjust plans due to unexpected money problems (financial adversity). You can secure your financial position by rebalancing assets toward dividend-paying equities and cash reserves.
Low-yield growth options fit early career stages, whereas income assets suit retirees needing reliable cash flows. Seeking professional guidance helps you manage unexpected risks effectively. Working with advisers in West Perth allows you to map out your long-term goals with clarity. Schedule a consultation to review your tailored strategy. More on this: Financial Mentors Wealth Management.
A commenter in the forumwealth.com thread "Forum Wealth Management: Home, Financial advisers …":
"Having been rather unsure of how to proceed with my money, after a messy divorce, I now feel very secure in how my financial future is being looked after." (https://forumwealth.com/)
That arc is plain: a messy divorce left the person unsure how to proceed; structured advice rebuilt the plan; the outcome was a secure view of the financial future. A reliable advice partner helps rebuild confidence when major life events disrupt your plans, and tailored financial planning turns uncertain funds into a structured, reliable income stream.
Balance Growth Assets With Capital Safety
You can protect your capital while securing a steady money coming in by balancing conservative assets with growth investments. Making financial decisions about your future often triggers worry, yet clear strategies remove this fear.
Retaining certain growth assets during the drawdown stage is easy to overlook, and it protects your capital against rising costs over a long retirement.
| Investment Strategy | Core Focus |
|---|---|
| Defensive Assets | Capital protection |
| Growth Assets | Long-term inflation defence |
Balancing these options creates stability and gives you a clearer basis for each drawdown decision.
You can speak with planners who map your future to manage your financial risks and align the mix with your goals.
Secure Predictable Yield With Bonds and Term Deposits
Bonds and term deposits provide predictable money coming in to help cover your daily lifestyle costs.
From client work, we see that balancing term deposits with government bonds offers stability while protecting against sudden market drops. Fixed interest assets reduce overall financial risks and create a steady cash flow during retirement.
Term deposits suit risk-averse investors needing short-term certainty, whereas mortgage funds fit those seeking higher returns from property loans. Government bonds act like a financial cushion for your portfolio. According to a speech by the European Stability Mechanism in 2024, unified capital markets expand investment options and promote equal access for consumers.
Comparing yields directly helps you build financial security. An initial appointment can help you walk through this assessment with clear cost information before you commit. More on this: Financial Mentors Wealth Management.
Generate Cash Flow From Franked Australian Shares
Australian dividend-paying equities provide steady money coming in for retirees through tax-effective cash returns. From client work we see that holding local shares helps generate extra cash via tax offsets. This strategy boosts overall yield because attached tax credits reduce the tax you owe on your investments.
You receive direct corporate payouts while benefiting from attached credits that reduce tax obligations. Building a portfolio of dividend-paying local shares supports sustainable retirement cash flow and turns company profits into regular, accessible funds for your daily living expenses.
To set up your personalised strategy, arrange a meeting to map out your personal finances and future objectives with a step-by-step review of franking benefits in your own name.
Optimise Super for Tax-Free Retirement Income
Moving your superannuation into the pension phase provides steady money coming in without paying tax on earnings. This step transforms your hard-earned savings into a reliable lifestyle.
Shifting assets during major life changes prevents severe financial adversity. Life events like moving, meeting local requirements, or managing demanding work arrangements change your overall financial position, so timing the pension-phase switch around those events matters more than most people expect.
Aligning your fund with your long-term goals creates clarity. Self-managed super (a member-managed superannuation fund) suits individuals wanting direct control over real estate investments. Conversely, standard retail funds fit people who prefer automated oversight. Choosing the right path reduces financial risks while lifting your retirement cash flow.
Book an appointment with Financial Mentors Wealth Management in West Perth to build your personalised financial plan and structure withdrawals around your goals.
Calculate Your Personal Withdrawal Rate Before You Draw Down
Calculating your target rate prevents unexpected money problems while keeping your retirement strategy on track. Self-managed super (a member-managed Australian fund) allows tailored cash flow choices, though self-managing investments, insurance, and retirement funds without professional help can feel overwhelming and lead to costly mistakes.
This complexity is why many retirees seek professional guidance to navigate their options. For example, those with assets or family in Canada might look for specialised retirement planning services Ontario from providers like Evergreen Wealth Management to ensure their wealth is managed effectively across borders.
- Sum total assets: Add all superannuation, cash, and growth investments to establish your total starting pool.
- Estimate inflation: Factor in Australian consumer price changes to protect your future purchasing power.
- Determine target income: Calculate your required annual money coming in to cover ongoing living costs.
- Divide income by assets: Split your needed annual draw by your total pool to reveal your initial percentage.
Your resulting drawdown percentage works as a spending baseline you revisit as living costs change. Choosing a conservative target suits cautious retirees wanting asset longevity, while a higher rate fits those prioritising early travel goals. Your ability to sustain the rate depends on how honestly you set the income figure in step three.
Speak with Financial Mentors Wealth Management to book a complementary initial consultation for your financial plan.
Protect Capital With a 2-Year Cash Buffer
Holding cash shields your retirement savings against market downturns and buys time so you avoid selling growth assets at lower values during temporary market drops.
In West Perth, experienced planners treat this setup as a shock absorber for your wealth. Maintaining reserves gives you control over pension-phase withdrawals without interrupting your regular income stream.
You protect your lifestyle from sudden market volatility and can manage financial commitments while allowing growth investments time to recover. The buffer also lets you consider sequenced returns: two years of living costs in cash means a weak market year does not force a sale at the wrong moment.
Would you like to build a resilient financial plan tailored to your long-term goals? Book a complementary initial consultation today and speak with the team about sizing the buffer to your spending.
When DIY Portfolio Management Fails Under Life Change
Managing investments yourself becomes difficult when major household changes reshape your financial position. Major transitions often require reorganising how money coming in is looked after, and managing assets without assistance can lead to unexpected money problems.
You might find adjusting your financial plan stressful during life transitions. Seeking financial advice helps protect your wealth strategies over time. Book an appointment for a periodic review to keep your long-term goals on track; working with a dedicated professional brings clarity and direction.
Among Financial Mentors Wealth Management’s Google reviews, a client’s specialist (5★) wrote:
"Easy to work with. Ready to answer questions and give great advice. Very happy with their service."
A commenter in the forumwealth.com thread "Forum Wealth Management: Home, Financial advisers …":
"Forum Wealth Management was recommended to me by my accountant whom I had known for 20 years. As a consequence, Forum Wealth Management has advised me on investments since January 2010."
Trusted long-term relationships provide a reliable foundation when adjusting your investment approach, and experienced guidance helps you navigate complex life changes with confidence.
Frequently asked questions
How do I shift from saving to spending in retirement?
You move from accumulating assets to pension-phase withdrawals by turning your balance into continuous money coming in. This process starts with setting up a structured drawdown plan aligned to your long-term goals. Booking an appointment with a financial adviser helps you assess your financial position and create a personalised financial plan.
What income-generating investments can I use?
Retirement portfolios often combine dividend-paying stocks, bonds, term deposits, and real estate to supply steady payments. Australian retirees can also use self-managed super to manage property assets or target tax-effective returns, and those researching the specialised Californian senior care sector can find helpful resources through the Assisted Living Real Estate Group. Selecting the right combination depends on your target growth and your tolerance for financial risks.
How can I optimise my portfolio for retirement income?
Portfolio optimisation requires balancing growth assets with defensive choices to manage market volatility while meeting your financial commitments. Scheduling a periodic review with a financial adviser allows you to adjust your holdings as your medium-term goals change. This tailored approach keeps your strategy aligned with your evolving financial position.
How do I take money out tax efficiently?
Accessing funds through superannuation after age 60 generally provides tax-free withdrawals and income streams under Australian rules. You can also structure distributions to protect eligible Centrelink entitlements and reduce tax on non-super earnings. Evaluating your complete financial position ensures you retain more of your money during life changes.
How much super do you need to retire at 60?
Your required super balance depends on your expected spending, total financial commitments, and desired lifestyle standards. Individuals facing unexpected money problems or managing an unexpected inheritance may require tailored projections. A professional wealth management review can clarify your personal target before you transition out of the workforce.
Keep Your Retirement Income Decisions Working Together
Generating income from investments in retirement still comes down to the same choices you met at the start: which bucket funds daily living, how much growth you keep for inflation, and when professional review replaces DIY guesswork.
From client work we see that structured plans help maintain steady cash flows. Managing your money coming in effectively supports long-term confidence in 2026.
Your initial meeting is step 01 of the process. The Financial Mentors Wealth Management advisers have provided professional planning advice since 2000. You can build a withdrawal strategy while protecting against unexpected money problems and create the future you want with a plan you own.
Book a consultation to review your retirement plan and own your tomorrow with a clear next step. More on this: Financial Mentors Wealth Management.