

Australian Public Service employees accessing defined benefit schemes face strict preservation age rules, and lump sum tax rates change with your age and the taxable versus tax-free mix of your benefit (plus the Medicare levy where it applies). Reviewing your financial position early lets you shape your public sector exit on your terms. Working with a dedicated financial adviser helps you map out the future you want with confidence.
Key Takeaways: Retirement planning for government employees Australia requires reaching age 60 to access transition to retirement income while managing defined benefit preservation and redundancy tax.
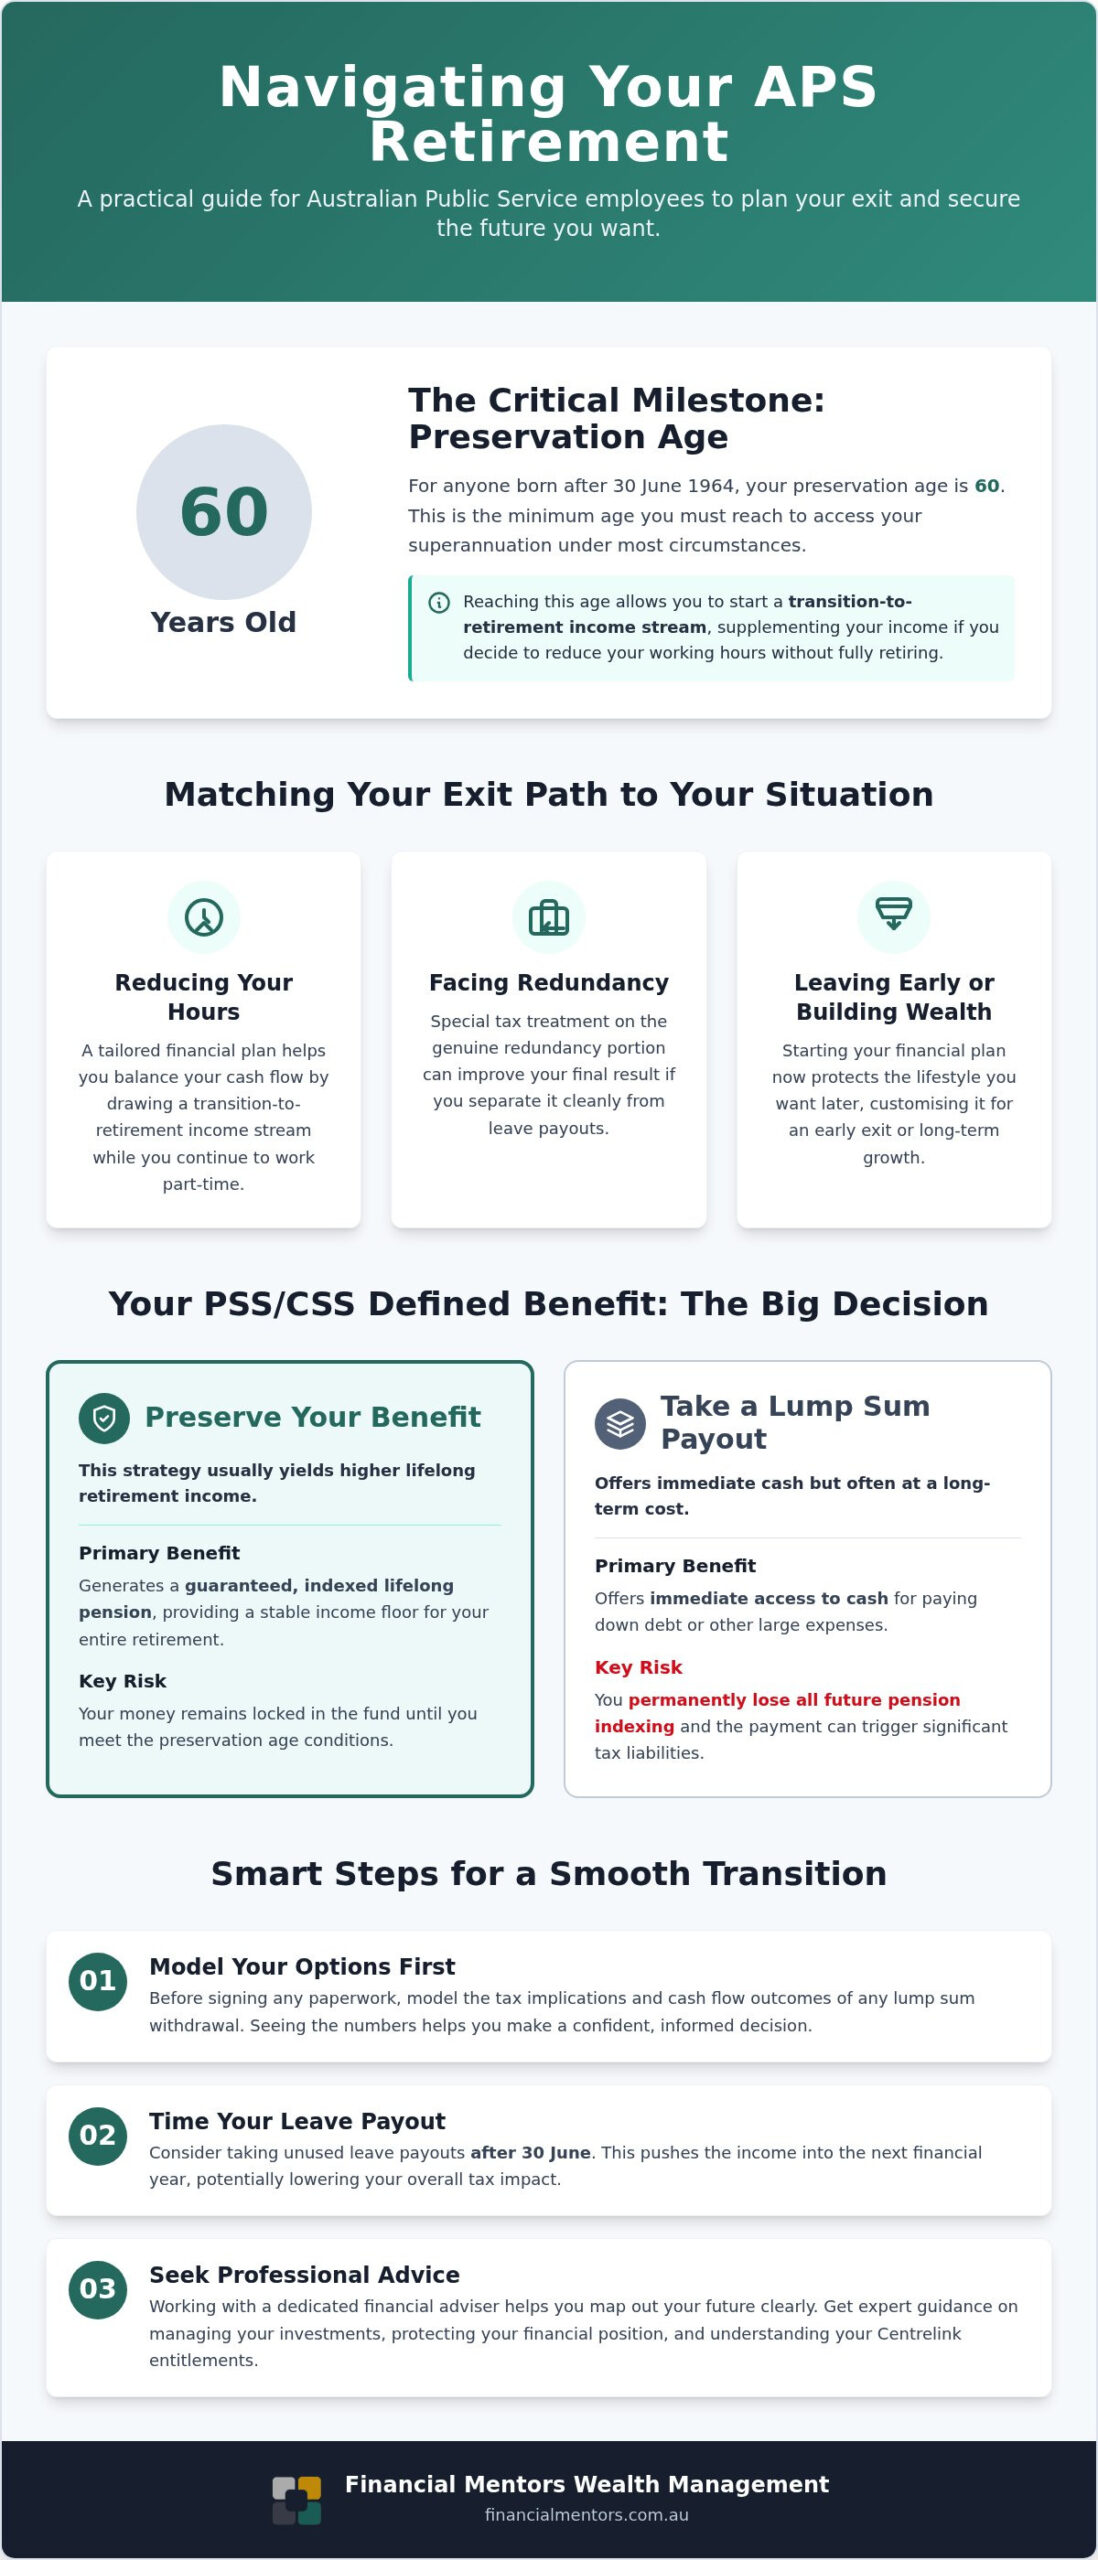
- Preservation age is 60 for all Australian public servants born after 30 June 1964.
- Except when you have a specific capital plan, preserving defined benefits usually yields higher lifelong income.
- Time unused leave payouts after June 30 to potentially reduce your overall tax bracket impact.
- The article’s comparison table shows that lump sums risk losing future indexation versus guaranteed pensions.
Match your APS exit path to the situation you face now
Your career stage sets the right steps for securing your financial position. Clients we see often hit sudden career changes or redundancies and feel deep anxiety about long-term goals. Clear choices, mapped early, restore confidence after major workplace shifts.
Three situations come up again and again:
- You want to cut hours before full retirement: a tailored financial plan balances ongoing cash flow while you draw a transition-to-retirement income stream.
- You face an early redundancy: special tax treatment on the genuine redundancy portion can improve your net result if you separate it cleanly from leave payouts.
- You are a younger APS worker still building wealth, or a senior staff member leaving early: starting the financial plan now (or customising it for an early exit) protects the lifestyle you want later.
Seeking advice from Financial Mentors Wealth Management helps you clarify your Centrelink entitlements (government pension rules) while protecting your savings. Make a time with the team for an initial consultation so your next step supports the future you want to create. More on this: Financial Mentors Wealth Management.
Reach preservation age before you start transition to retirement
You access super under transition-to-retirement rules only after you reach preservation age. For anyone born after 30 June 1964, preservation age is 60 (older birth cohorts had lower ages, stepping up to 60).
Government employees often overlook the precise timing for reducing hours before full retirement. Checking your date of birth against the preservation age rules early prevents delay when you are ready to ease back.
According to the ABS 2024 Retirement and Retirement Intentions release, Australians now leave the workforce at an average age of 66 years. Once you reach preservation age you can draw super as an income stream while you keep working, which supplements reduced hours without a full exit.
Speak with Financial Mentors Wealth Management to map this step against your long-term goals. Early planning suits workers who want to ease into leaving work early without sacrificing lifestyle. More on this: Financial Mentors Wealth Management.
Keep PSS and CSS defined benefits working for lifelong income
Preserving your defined benefit superannuation options generally yields higher lifelong retirement income than taking an immediate lump sum.
Public servants often feel pressure to leave early and reach for cash. Choosing the wrong strategy can permanently reduce your indexed pension. Defined benefit schemes calculate final payouts using set formulas based on your tenure and final salary rather than investment market movements.
One practical path is to keep your defined benefits within the plan so the untaxed component can build prior to preservation age, then take the indexed pension when you qualify.
| Exit Option | Primary Benefit | Key Risk |
|---|---|---|
| Preserving Benefit | Generates guaranteed, indexed lifelong pension income | Money remains locked until meeting preservation age |
| Lump Sum Payout | Offers immediate access to cash for debt paydown | Triggers potential tax liabilities and loses future indexing |
A familiar pattern, turned into a clear result: a public servant nearing exit panics about cash needs, almost takes the lump sum, then pauses to compare the indexed pension against a one-off payment. Keeping the benefit in the scheme protects lifelong indexation; taking the lump sum frees cash now but ends that indexation and can trigger tax. Modelling both paths before HR paperwork is signed is what separates a stable income floor from a smaller, finite balance.
Managing investments, super, and insurance without guidance can lead to costly mistakes. Tailored help from a Financial Mentors Wealth Management adviser protects your financial position, including estate planning and Centrelink entitlements during an early exit. More on this: Financial Mentors Wealth Management.
If the rules feel heavy right now, schedule an initial meeting to review your long-term goals in plain terms.
Accountants frequently connect public sector workers with financial advisers for ongoing guidance.
A commenter in the forumwealth.com thread "Forum Wealth Management: Home, Financial advisers …":
"Forum Wealth Management was recommended to me by my accountant whom I had known for 20 years. As a consequence, Forum Wealth Management has advised me on investments since January 2010." (https://forumwealth.com/)
Long-standing professional relationships help public servants navigate choices such as defined benefit preservation so investments stay aligned with changing retirement goals.
Model lump sum tax and cash flow before you withdraw
Your net payout depends on separating taxable elements from tax-free components. Choosing a cash lump sum over a monthly income stream needs careful review. Members often fear the wrong choice and miscalculate final tax liability, which reduces long-term reserves.
Your age and scheme structure set the final tax rates. Uncontrolled withdrawals accelerate the drain on the balance you will need later. Model cash flow before you withdraw; income projection work protects long-term goals and shows how the choice affects Centrelink entitlements.
Book a Financial Mentors Wealth Management session when you want those figures in front of you before you sign anything. More on this: Financial Mentors Wealth Management.
Tip: Always request a custom tax calculation statement from your scheme administrator before signing off on a lump sum payout.
Use genuine redundancy tax concessions without mixing them up with leave
An Australian Public Service (APS) voluntary redundancy payout receives special tax treatment that separates genuine redundancy payments from standard income.
In practical advisory work, people often juggle relocation or new financial commitments after leaving a role. The Australian Taxation Office sets a specific tax-free base limit plus an additional tax-free amount for every completed year of service. That portion is tax-free.
Any remaining payout above this limit is taxed as an employment termination payment at concessional rates, up to a designated cap. That treatment is an income tax concession on the genuine redundancy portion, not a capital-gains or investment shield. Accrued leave paid out during a redundancy does not qualify for the genuine redundancy tax-free limit and is taxed separately.
Knowing where each dollar sits helps you protect your financial position and plan the next step with confidence. Book an appointment to walk through your own thresholds before you accept an offer.
Time your unused leave lump sum to limit the tax hit
Your unused leave payout is taxed as a lump sum, with lower concessional rates applying to long service leave accrued before mid-1993.
Taking leave as a payout can shift your taxable income sharply in a single financial year. Receiving the payout just after 30 June can reduce your overall tax bill compared with exiting in May, because the income lands in a different financial year and may ease pressure on your bracket.
Calculate the amounts with a clear review of service dates and leave types, then lock your final departure date once the tax picture is plain. Tailored financial advice keeps the exit strategy from eroding savings you have already earned. An adviser in West Perth can help you weigh timing and structure so the transition supports your goals.
Five practical steps to move from public service into retirement
A clean transition rests on clear financial commitments and an updated financial position before you leave the workforce. Major household changes often mean reorganising how money is looked after; doing that in order protects lifestyle.
- Notify HR: Inform your department about your plan for leaving work early (early retirement).
- Review rules: Check your government pension rules (Centrelink entitlements) to confirm your eligibility dates.
- Adjust workload: Consider cutting down hours (transition to retirement) to ease into your new routine gradually.
- Organise finances: Adjust your financial plan to align with your medium-term goals and long-term goals.
- Start drawdown: Begin income streams from your superannuation fund or self-managed super to cover daily living expenses.
Regular review sessions with an adviser keep the strategy fit for purpose as rules and your life change. Speak with the team to schedule a complementary initial consultation when you are ready to put these steps in order.
When an early lump sum payout costs you more than it frees up
Cashing out early can compromise long-term goals by forfeiting guaranteed, inflation-linked income streams.
If a previous adviser relationship has ended, you may feel unsure where to turn. Fresh support can clarify your financial commitments again.
A defined benefit pension behaves like a steady personal engine; a lump sum turns that engine into a finite fuel tank. Preserving the scheme protects you against market downturns and keeps lifelong indexation. An early cash-out drops that indexation for good.
Preservation suits risk-averse retirees who need certainty. Early payouts fit people with a specific alternative capital plan and a clear way to replace the lost income floor. Schedule an initial consultation when you want those two paths compared against your own figures.
How tailored financial advice protects the value of your public payout
Expert planning aligns your government benefits with your personal long-term goals. Complex defined benefit schemes need a dedicated strategy, not a generic template.
Tailored advice helps public sector workers move into retirement with a plan that turns static superannuation rules into active wealth management (financial planning for high-net-worth clients). Professional guidance helps you navigate Centrelink entitlements while protecting savings against financial risks, and helps you balance income, risk, and capital access in line with how retirement income is meant to work in practice.
Your initial meeting is where goals, constraints, and costs are put on the table so you can decide the next step with clear information. Regular reviews help you adapt when your situation changes.
A commenter in the forumwealth.com thread "Forum Wealth Management: Home, Financial advisers …":
"Finding a financial adviser open to creating an ethical portfolio with thoughtful analysis, supportive commitment and good results has been very reassuring."
"Highly recommend Murray, he is lovely and very helpful, also responsive. Glad
Ongoing, personalised advice helps public sector employees secure retirement savings while staying true to personal values.
Frequently asked questions
What is an APS voluntary redundancy?
An Australian Public Service voluntary redundancy occurs when an employee willingly accepts an offer to resign from their role. This offer usually includes a severance payment.
Is an APS redundancy tax-free?
Part of a genuine redundancy payout receives special tax-free treatment up to limits set by tax laws. Remaining amounts face taxation rules based on your overall income and the employment termination payment caps that apply.
What happens to my PSS or CSS super if I take redundancy?
Your PSS or CSS superannuation scheme calculates your benefit based on your final average salary, your years of service, and your age. You can choose between taking a deferred pension or receiving an immediate benefit depending on your scheme rules.
What age qualifies for transition to retirement?
You can start cutting down hours once you reach your preservation age. For anyone born after 30 June 1964 that age is 60. This strategy lets you access super while continuing to work part-time.
Can I receive a lump sum for unused leave?
Unused annual leave and long service leave are paid out as cash when you leave the public service. Taxation applies to these lump sums depending on your period of service and when the leave accrued.
Securing your financial future in 2026
Preparing for life after public service needs the same through-line you started with: which exit path fits your situation, when preservation age and tax rules help or hurt, and whether a pension, a lump sum, or a staged transition best funds the lifestyle you want.
Proper guidance turns uncertainty into a workable financial plan. Tailored advice helps you align superannuation with long-term goals, use Centrelink entitlements correctly, and structure savings for cutting hours or leaving early.
Since 2000, Financial Mentors Wealth Management advisers have guided public servants through these decisions. Own your tomorrow with a clear first step: book a complementary initial consultation and make a time to map the future you want to create. More on this: Financial Mentors Wealth Management.