

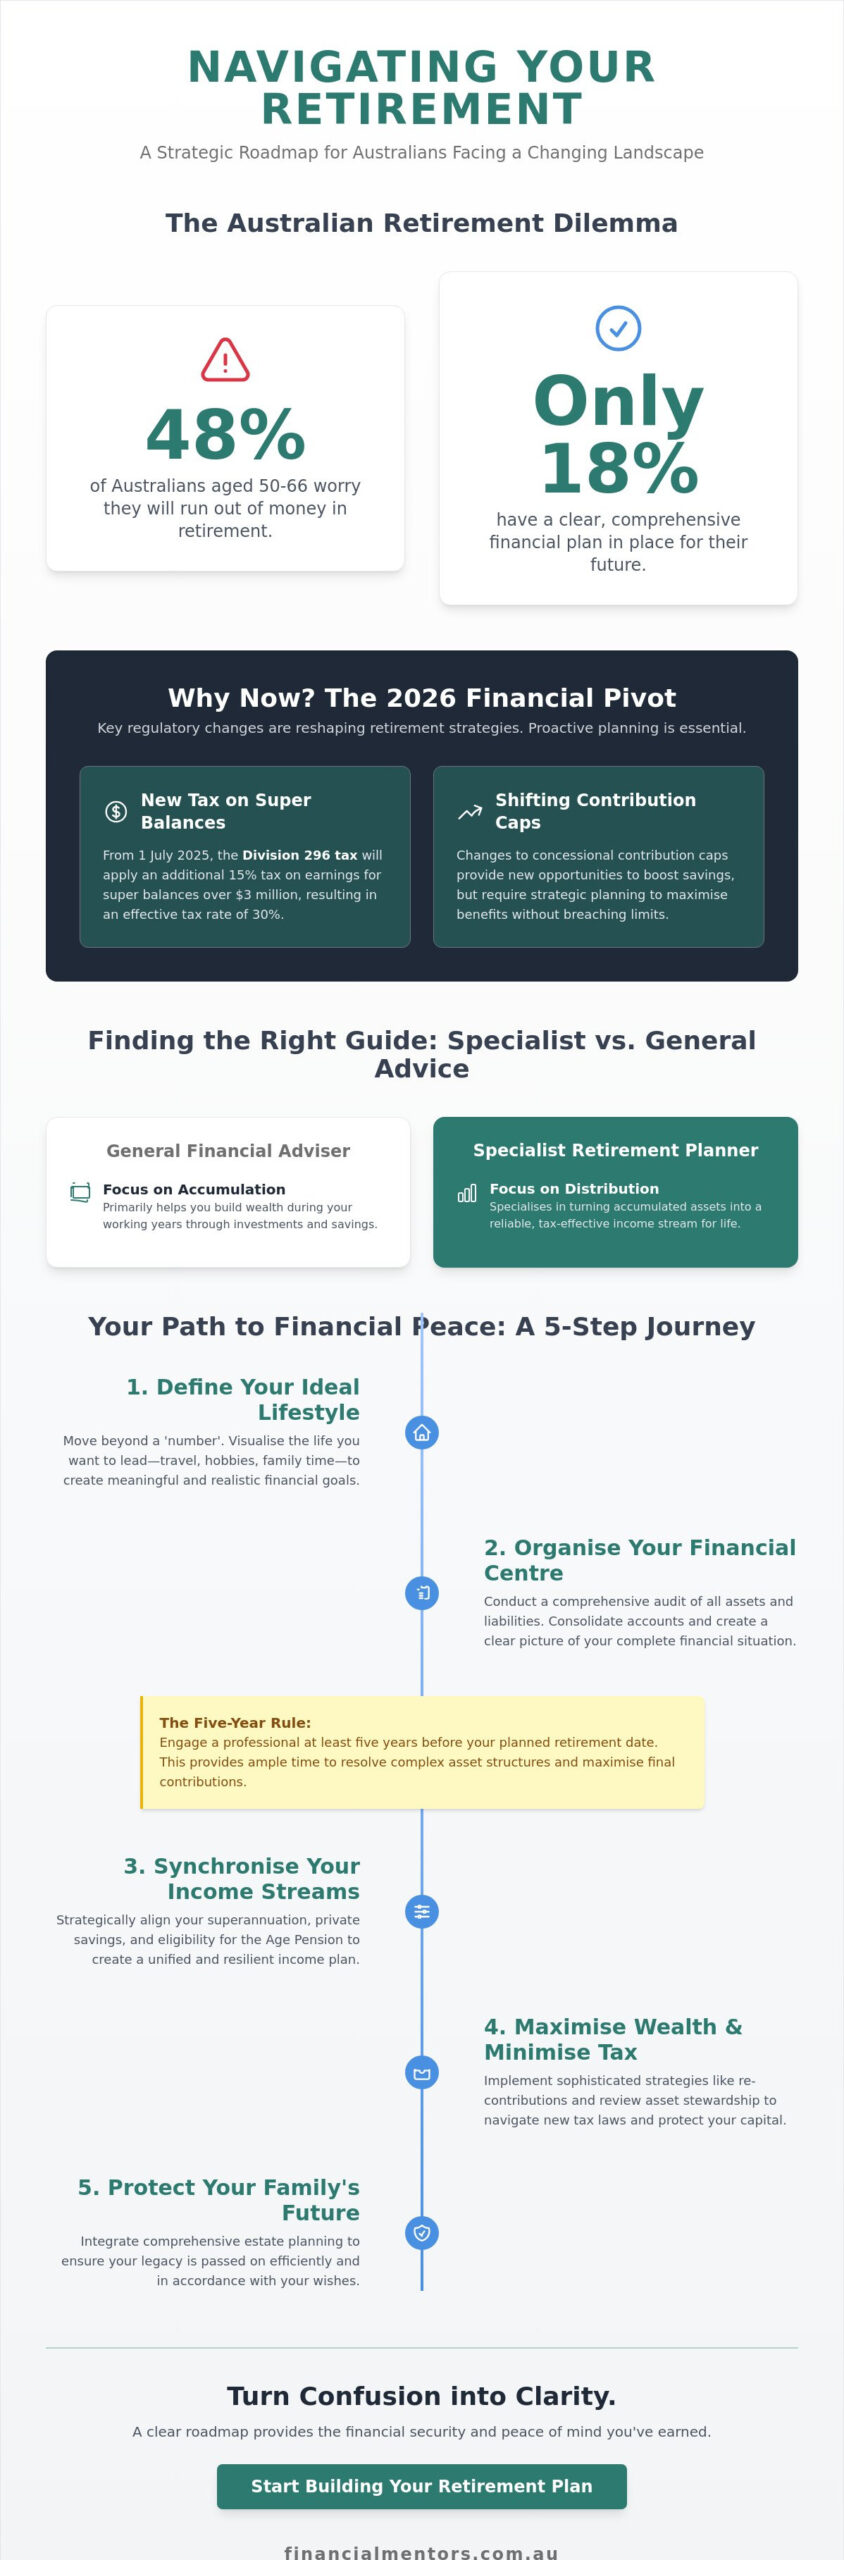
Did you know that 48% of Australians aged 50 to 66 worry they’ll run out of money in retirement, yet only 18% have a clear plan in place? It’s a quiet weight to carry, particularly with the new Division 296 tax on high super balances and shifting contribution caps arriving this July. You’ve spent decades working hard, and it’s only natural to feel some anxiety about whether your savings can keep pace with rising healthcare costs. Finding the right retirement planners shouldn’t be about just crunching numbers; it’s about finding a partner who understands that your financial security is the foundation of your family’s peace of mind.
We agree that the complexity of the Australian financial system can feel overwhelming, but it’s possible to turn that confusion into a structured path forward. This guide will show you how a professional partner can help you maximise your retirement income while minimising tax through strategic stewardship of your assets. We’ll preview how to align your superannuation, lifestyle goals, and estate planning into a clear roadmap for 2026 and beyond. If you have a dedicated strategy in place, then you can stop worrying about the “what-ifs” and start focusing on the golden years you’ve truly earned.
Key Takeaways
- Understand the distinction between general financial advice and the specialised support provided by retirement planners to help you navigate life’s major transitions.
- Learn how to synchronise your superannuation with the Age Pension and asset limits to ensure your income remains steady throughout your post-work years.
- Discover the difference between the cost of advice and the long-term value of a mentor who prioritises transparency and your personal goals.
- Explore the step-by-step process of defining your ideal lifestyle and organising your financial centre through a comprehensive asset and liability audit.
- See how combining wealth creation strategies with professional tax return preparation can simplify your financial life and protect your family’s future.
Understanding the Role of Retirement Planners in Australia
What does it mean to truly prepare for the end of your working life? For many Australians, this transition feels like stepping off a familiar path into unknown territory. While a general financial adviser might help you build wealth during your younger years, specialised retirement planners focus on the delicate art of turning those accumulated assets into a reliable, tax-effective income stream that lasts as long as you do. They act as a bridge between your career and your future, ensuring that the complex machinery of Superannuation in Australia works in your favour.
Why is 2026 such a pivotal moment to review your trajectory? With the introduction of the Division 296 tax on high super balances and the increase of the concessional contribution cap to $32,500 on 1 July 2026, the rules of the game are changing. If you don’t adjust your strategy now, you might find yourself paying more tax than necessary or missing out on new opportunities to boost your savings. A retirement specialist looks beyond simple investment returns; they examine how these regulatory shifts impact your specific lifestyle goals and family protections.
The Emotional and Financial Shift of Retirement
Moving from a mindset of accumulation to one of distribution is often the biggest hurdle for our clients. After decades of watching your balance grow, it can be confronting to start drawing it down. Have you ever wondered if your “number” is actually enough to sustain the lifestyle you’ve imagined? This is where the mentor relationship becomes vital. By focusing on lifestyle design rather than just a bank balance, a planner helps you address the common fear of running out of money. It’s about creating a structured plan that validates your aspirations while providing the safety net your family deserves. If you have a clear roadmap, the stress of the unknown begins to fade.
When Should You Engage a Professional?
We often recommend the “Five-Year Rule” for those approaching their final day of work. If you begin the dialogue at least five years before you intend to retire, you have enough time to resolve complex asset structures and maximise your final contributions under the current caps. If your financial setup involves multiple properties, a self-managed super fund, or intricate estate planning needs, DIY management can quickly become a source of anxiety. Major life transitions, such as downsizing your home or receiving an inheritance, are natural points to seek a steady hand. Working with retirement planners allows you to delegate the technical burden so you can focus on the milestones that matter most.
Navigating the Complexity of the Australian Retirement System
The Australian retirement system is often described as a three-pillar model, but for most of us, it feels more like a complex puzzle with moving pieces. Your superannuation acts as the engine room of this system. It’s the primary vehicle that will drive your lifestyle once the regular paycheques stop. However, the way this engine performs depends heavily on how it interacts with other components, such as the Age Pension and your private savings. Expert retirement planners help you synchronise these elements so they work together rather than in opposition.
As we move into 2026, the landscape is shifting. With the general transfer balance cap increasing to $2.1 million, there’s more room to move your savings into a tax-free retirement phase. Yet, new challenges like the Division 296 tax on high super balances mean that those with significant savings must be more strategic than ever. If your total super balance sits between $3 million and $10 million, you’ll face an effective tax rate of 30% on realised earnings from 1 July 2026. This isn’t just a hurdle; it’s a prompt to review your stewardship of these assets to ensure your family’s legacy remains protected.
Superannuation and Retirement Fund Strategies
Choosing the right structure for your super is a foundational decision. While industry and retail funds offer simplicity, a Self-Managed Super Fund (SMSF) provides a level of control that many find appealing as they approach retirement. Have you considered a recontribution strategy? By withdrawing and then recontributing funds back into super, you can often reduce the tax your beneficiaries might eventually pay on the taxable component of your death benefit. It’s a practical way to look after your loved ones while staying within the increased non-concessional cap of $130,000. Matching your investment profile to your specific retirement timeline ensures you aren’t taking unnecessary risks when you can least afford them.
Tax and the Age Pension: A Delicate Balance
Many Australians find themselves in the “middle ground,” where they have too much for a full pension but not enough to feel completely secure. As of March 2026, the Age Pension for a single person is $31,223 per year. Managing the asset and income tests effectively can be the difference between receiving a part-pension or none at all. This is where we see the true value of integrated planning. We believe that professional tax return preparation should be a year-round strategic conversation. If you view your tax obligations through the lens of your retirement goals, you can identify opportunities for tax-free income streams that a standard “once-a-year” approach might miss. This steady, methodical oversight creates a sense of order and helps you transition into preservation age with quiet confidence.
Evaluating Retirement Planners: Beyond the Fee Structure
Choosing a partner for your financial future is one of the most significant decisions you’ll make. While it’s tempting to focus solely on the “cost of advice,” the true measure of a relationship lies in the “value of advice.” If a strategy helps you avoid a costly tax mistake or provides the confidence to enjoy your savings without guilt, then the return on that investment far outweighs the initial fee. Transparent retirement planners will always be happy to discuss their fee structures openly; this clarity is the bedrock of a mentor relationship. If a provider is vague about how they’re compensated, it’s often a sign that the partnership may not be as client-focused as you deserve.
Before you commit, ensure your chosen professional holds an Australian Financial Services Licence (AFSL) or is an authorised representative of one. This isn’t just a legal requirement; it’s your assurance that they’re bound by professional standards and a duty to act in your best interests. You should also watch for red flags, such as high-pressure tactics or a “one-size-fits-all” approach. A wise mentor takes the time to listen to your unique story before suggesting a path forward. If the conversation feels more like a sales pitch than a consultation, it might be time to look elsewhere.
Different Models of Financial Advice
In Australia, you’ll generally find two models: bank-aligned planners and independent or non-aligned offices. Bank-aligned advisers may be limited to a specific range of products, whereas independent planners often have the freedom to choose strategies that best fit your milestones. If you’re looking for a seamless experience, a wealth management office that offers integrated tax return preparation can be incredibly beneficial. This setup ensures that your investment strategy and your tax obligations are always in conversation. Every recommendation should be documented in a Statement of Advice (SOA), which acts as your personal roadmap, detailing exactly why certain strategies were chosen for you.
Questions to Ask During Your Discovery Session
Your first meeting is as much about you interviewing them as it is about the financial audit. You might start by asking, “How do you measure success for your clients beyond just investment returns?” This helps you gauge whether they value your peace of mind as much as your balance sheet. It’s also vital to ask about their experience with estate planning and intergenerational wealth; you want to know that your family’s legacy is in steady hands. To ensure they can navigate the nuances of the social security system, you should ask them to explain their specific process for helping clients manage Age Pension asset and income tests effectively. These questions will help you identify a partner who is truly attuned to the emotional and practical nuances of your retirement journey.
The Strategic Roadmap to Your Ideal Retirement
Success in retirement doesn’t happen by accident; it’s the result of a deliberate, step-by-step process. When you work with professional retirement planners, you aren’t just buying a document. You’re entering a collaborative cycle designed to bring order to your financial life. This journey begins with the Discovery Phase, where we define what “enough” looks like for you. With only 18% of Australians currently having a clear plan in place, this first step is often the most transformative. It’s the moment you stop guessing and start knowing.
Once your vision is clear, we move through a methodical sequence of planning:
- Asset and Liability Audit: We organise your current financial centre, looking at everything from super balances to property and personal debts.
- Strategy Formulation: This is where we build your roadmap, integrating the tax changes and contribution caps we’ve discussed to ensure your wealth is working as hard as possible.
- Implementation: Your mentor helps you put the plan into action, handling the technical heavy lifting so you can stay focused on your transition.
- Ongoing Review: Life is rarely a straight line. We meet regularly to adjust your strategy for legislative shifts or personal changes, such as the arrival of a grandchild or a change in health.
If you’re ready to start this journey, our retirement planning services provide the structured support you need to move forward with confidence.
Setting Realistic Retirement Goals
Have you thought about the difference between your “needs” and your “aspirations”? A robust plan distinguishes between the essentials, like groceries and rates, and the dreams, like overseas travel or a new caravan. We use sophisticated modelling to show how different scenarios, like a phased retirement where you work two days a week, might impact your longevity. It’s also vital to account for the “silent” factors. For instance, with healthcare costs rising at approximately 7% annually, your plan must be resilient enough to absorb these cost-of-living adjustments over a thirty-year horizon.
Estate Planning: The Final Piece of the Puzzle
Wealth creation is only half the story; stewardship of that wealth for the next generation is the other. Many people believe a Will is sufficient, but in the context of Australian superannuation, it’s often only the beginning. We focus heavily on Binding Death Benefit Nominations (BDBNs). These instructions ensure your superannuation, which often sits outside your estate, goes exactly where you intend. By coordinating your estate planning advice with your overall financial strategy, you can feel confident that your family is protected and your legacy is secure. This holistic approach ensures that your hard work today continues to benefit your loved ones long after you’ve finished your career.
How Financial Mentors Wealth Management Guides Your Journey to Financial Peace
Your financial journey is deeply personal. It isn’t just about percentages or market indices; it’s about the life you’ve built and the legacy you wish to leave behind. Unlike some retirement planners who focus only on the transaction, our “Wise Mentor” approach at Financial Mentors Wealth Management prioritises a long-term partnership. We act as your trusted guide, sitting across the table to help you make sense of the choices ahead. This stewardship means we’re as invested in your peace of mind as you are. We’re here to listen, observe, and provide the steady hand you need during major life transitions.
We’ve found that true financial order comes from seeing the whole picture. By integrating professional tax return preparation with our wealth creation strategies, Financial Mentors Wealth Management removes the friction often found when dealing with separate firms. Your tax position and your investment goals should never be at odds. When these elements are in harmony, you can move forward with a sense of calm, knowing that every detail is being managed with precision. Murray Frean and the team are dedicated to this level of personalised care, ensuring that your assets are protected through every milestone. It’s a methodical way to ensure your financial centre remains strong.
A Tailored Approach to Wealth Management
Does a “one-size-fits-all” portfolio really reflect your unique aspirations? We don’t think so. At Financial Mentors Wealth Management, we move away from cookie-cutter solutions to create bespoke financial roadmaps that adapt to your specific needs. Our advice is backed by an Australian Financial Services Licence (AFSL), which means we have a legal and ethical duty to put your interests first. Having a dedicated wealth management office means you always have a point of contact who knows your story. It’s about the stability that comes from knowing your future-proofing is in capable hands. If you have a plan that is built specifically for you, then the noise of the market becomes much easier to ignore.
Starting Your Conversation Today
Your first meeting with a Financial Mentors Wealth Management adviser is designed to be a comfortable, low-pressure dialogue. We’ll start by listening to your concerns and your dreams for the future. We’ll help you organise your finances to reduce immediate stress, providing a clear view of where you stand today. If you’re feeling overwhelmed by the complexity of the current system, then this initial conversation is the first step toward clarity. We’re here to help you build the confidence you need to enjoy the years ahead. It’s a simple, step-by-step process that begins with a single invitation for dialogue.
Enquire about your personalised retirement roadmap with Financial Mentors Wealth Management
Taking the First Step Toward Your Golden Years
Preparing for the next stage of your life is more than a financial exercise; it’s an act of intentional planning for your future self and your loved ones. We’ve explored how a clear roadmap can transform confusion into confidence, especially when you have a partner to help you navigate the shifting landscape of 2026. By integrating wealth creation with professional tax return preparation and specialised estate planning, you ensure that every part of your financial life is working in harmony. Expert retirement planners don’t just manage assets; they provide the stability that comes from being truly prepared for life’s inevitable changes.
Financial Mentors Wealth Management has been AFSL licensed since 2003, providing the steady, expert guidance needed to protect your hard-earned legacy. If you’re ready to replace anxiety with a structured path forward, we’re here to sit across the table and listen to your story. Begin your journey toward a secure retirement with Financial Mentors Wealth Management today. You’ve worked hard to reach this transition, and now it’s time to ensure your post-work years are as rewarding as you’ve always imagined.
Frequently Asked Questions
How much does a retirement planner cost in Australia?
The cost of professional advice varies based on the complexity of your financial situation and the level of ongoing stewardship you need. Most planners charge a fee for the initial Statement of Advice and a separate fee for the implementation of those strategies. If you’re looking for a partner for your journey, it’s best to discuss these costs transparently during your first meeting to ensure the value of the advice aligns with your personal goals.
What is the difference between a financial planner and a retirement planner?
A general financial planner often focuses on wealth accumulation for younger clients, while retirement planners specialise in the transition from working life to drawing a sustainable income. They have deep expertise in complex areas like the Age Pension, tax-effective drawdown strategies, and the specific regulations that apply once you reach preservation age. If you’re within five to ten years of retiring, a specialist can provide the nuanced guidance required for this major life milestone.
Can I manage my own retirement planning without a professional?
You can certainly manage your own finances, but the Australian retirement system involves intricate rules that change frequently. If you have a straightforward setup, a DIY approach might suffice; however, if you have multiple assets or complex family needs, professional oversight helps you avoid expensive tax mistakes. Would you feel more confident knowing a mentor is watching for regulatory shifts, such as the 2026 changes to superannuation tax on high balances?
How much superannuation do I need to retire comfortably in Australia?
According to the ASFA retirement standard as of March 2026, a single homeowner needs a lump sum of approximately $630,000 for a comfortable retirement, while a couple needs $730,000. These figures support an annual income of about $54,840 for a single person and $77,375 for a couple. If your aspirations include frequent travel or specific lifestyle goals, then you may need to build a larger balance to ensure your savings last for thirty years or more.
What happens to my super when I retire?
Once you reach your preservation age and retire, you can generally choose to keep your super in an accumulation account or move it into a tax-free retirement pension. Moving your funds into a pension account allows you to receive regular income payments while the remaining balance continues to grow in a tax-effective environment. If you choose this path, you must stay within the general transfer balance cap, which increased to $2.1 million on 1 July 2026.
Does a retirement planner help with the Age Pension application?
Yes, retirement planners often provide vital support in navigating the Centrelink system to ensure you receive your rightful entitlements. They help you understand how the asset and income tests apply to your circumstances, which is important given the single Age Pension is $31,223 per year as of March 2026. If you structure your assets thoughtfully, you might be able to maximise your part-pension payments and benefit from the Pensioner Concession Card.
How often should I meet with my retirement planner?
Most people find that a formal review at least once a year provides the right balance of oversight and flexibility. If there are significant changes to your health, family situation, or Australian tax laws, an earlier meeting ensures your strategy remains relevant. Does your current roadmap still reflect your unique aspirations, or has your vision for your golden years evolved since you last sat down to plan?
Is estate planning included in retirement planning services?
We believe that estate planning advice is a core component of any comprehensive retirement strategy. It’s about ensuring your wealth creation efforts eventually benefit your loved ones through tools like Binding Death Benefit Nominations. While we provide the strategic advice needed to structure your assets for your beneficiaries, we don’t draft legal documents; we work in partnership with your legal professionals to ensure your entire plan is organised and secure.